When implied volatility sits rich against the expected move, we favor short-vol spreads like iron condors or credit verticals; when the expected move looks too small for a plausible surprise, we favor buying straddles or strangles. Either way, size every position off Vega exposure, not just premium, and confirm tight quotes before entry. The checklist and worked examples below show exactly how.
TL;DR:
- Divide the at the money straddle price by the share price to estimate the market's expected percentage move before choosing strikes.
- Use short volatility when the implied move exceeds a reasonable outcome; reserve long volatility for underpriced catalysts when premiums are not already expensive.
- A 10 point volatility drop costs about $0.80 per contract at $0.08 Vega, so size positions by dollar Vega and cap premium risk.
- Target 3 to 14 days to expiration, avoid wide quotes and thin open interest, and set exits tied to price and volatility before the announcement.
- Most post earnings repricing unfolds within one or two sessions; compare the stock's move with its sector or index when macro volatility is high.
Table of Contents
- Why options reprice sharply after earnings: IV crush, expected move math, and Vega
- Which strategies work after earnings: short-vol, long-vol, and directional rules
- Execution checklist: entry rules, sizing, exits, and liquidity checks
- Two worked trade examples: a short-vol spread and a long straddle
- How to source vetted, ranked post-earnings ideas fast
- What post-earnings drift means for options traders and how long it lasts
- Reading post-earnings moves across different market conditions
- Typical risks in post-earnings trades and how to manage them
- Using earnings surprise and analyst revisions in your trade decisions
- Pre-earnings versus post-earnings IV and what it means for premiums
- Staying disciplined when the print hits
- Get ranked post-earnings ideas before the open
- FAQ
- Sources
Why options reprice sharply after earnings: IV crush, expected move math, and Vega
Implied volatility typically climbs into an earnings print as traders bid up protection and speculation, then drops sharply once the number is out. Options education resources describe this pattern as the implied volatility and IV crush effect: premium can shrink even when the stock moves in the direction you expected, because the volatility component of price collapses faster than the directional gain builds it back up.
To judge whether a position makes sense, you need the expected move first. A quick method: take the price of the at-the-money straddle and divide by the stock price to get a rough percentage move the market has priced in. A related shortcut comes from Fidelity's earnings trading guide, where 16% annualized IV corresponds to roughly a 1% expected daily move, since 16 is close to the square root of the number of trading days in a year.
- Step 1: convert annualized IV to a daily figure by dividing by roughly 16.
- Step 2: multiply that daily percentage by the stock price to get a dollar expected move.
Vega math example: if a contract has a Vega of $0.08 and implied volatility drops 10 points after the print, that single contract loses roughly $0.80 in value from volatility alone, separate from any price movement. As Fidelity's volatility primer notes, Vega measures the dollar change per 1% move in implied volatility, which is why converting Vega to dollars-per-contract before sizing a position matters more than watching premium alone.
Which strategies work after earnings: short-vol, long-vol, and directional rules
The right structure depends on how rich implied volatility looks relative to what you think will actually happen, not on habit or whichever trade feels familiar.
- Short-vol spreads (credit verticals, iron condors) fit best when IV percentile is high and the straddle-implied expected move looks larger than a reasonable outcome; research comparing long- and short-volatility strategies around earnings found that short-vol approaches often outperformed long-vol ones across multi-year samples, but only once combined with IV filters and spread-width limits.
- Long-vol trades (straddles, strangles) make sense when the market's priced-in move looks too conservative for the catalyst, for example a company facing a binary regulatory decision alongside its earnings release, and when IV is not already so expensive that a crush wipes out any directional gain.
- Directional spreads and single-leg plays suit a trader with a specific thesis, say a view that margins will beat guidance, where defining max loss with a debit spread lets you express that view without the full cost of naked options.
Skew matters at every step. A steep put skew often signals the market is pricing downside risk more richly than upside, which should push your strike selection toward asymmetric structures rather than symmetric ones. Shorter days-to-expiration concentrate both gamma and the Vanna/Volga adjustments that move pricing as volatility shifts, so a 3-day options chain reacts very differently to the same IV change than a 30-day one.
Pro Tip: Check IV percentile before direction. A stock can look "cheap" on raw IV and still be expensive relative to its own history.
Execution checklist: entry rules, sizing, exits, and liquidity checks
A repeatable checklist keeps earnings trades from becoming guesswork, supported by tools like the EOD Drawdown Tracker — Profirms that help manage drawdown limits effectively.
- Entry: target roughly 3 to 14 days to expiration, pick strikes anchored to the expected move and adjusted for skew, and avoid anything with a wide bid-ask spread or thin open interest.
- Sizing: cap Vega exposure per trade (for example, no single position's Vega exceeds a set dollar amount relative to account size) and limit premium at risk to a fixed percentage of your trading capital.
- Exits: set a profit target and a stop before you enter, tied to both the underlying's move and the change in implied volatility, since a position can lose money on an IV crush alone even with a favorable price move.
- Liquidity: require a minimum quote width (a few cents on liquid names, wider tolerances only on names with real volume) and use limit orders, including limit-on-open orders when trading the first print after the announcement.
A simple Vega-based sizing calculation: if your account risk limit is $500 of Vega exposure and a spread carries $0.12 of Vega per contract, four contracts put you at $48 of Vega, well inside the cap; scaling to 40 contracts would blow past it.
Pro Tip: Write your exit rule down before the trade, not after you see the first print. Discipline under a gap is the hardest thing to improvise.
Two worked trade examples: a short-vol spread and a long straddle
Short-vol example: sell a 10-point-wide iron condor for $2.00 credit with breakevens at the short strikes plus and minus that credit. If implied volatility drops 10 points after the print, the surviving spread's value typically falls as well, letting you buy it back cheaper and keep a larger share of the credit, assuming the stock stays within your short strikes.
Long straddle example: buy a straddle for $6.00 total cost, meaning the stock must move more than $6.00 in either direction from the strike to profit at expiration. A straddle commonly carries a combined Vega near $0.15 to $0.20 per share depending on tenor, so a 10-point IV drop can cost $1.50 to $2.00 of value even before accounting for the directional move, which is why a long-vol trade needs a real surprise, not just any move, to overcome the IV crush working against it.
- Prefer the short-vol structure when the implied move looks rich and you expect a contained reaction.
- Prefer the long straddle when you have reason to doubt the market's expected-move pricing, such as a pending guidance change or litigation outcome layered onto the print.
How to source vetted, ranked post-earnings ideas fast
A usable idea needs five things checked before you ever look at a chart: entry and exit levels, Vega impact, IV percentile relative to the stock's own history, liquidity (spread and open interest), and a short note on what could go wrong.
- MorningOptions runs a 5 AI pipeline to vet, score, and surface options trade ideas alongside strategy education, at Morningoptions.
- We deliver options briefings every market morning with ranked, specific contract ideas and entry levels, built for active retail traders.
- The free daily briefing is paired with a paid tier that unlocks additional scanning tools for researching tickers on demand.
A workable morning routine: run the pre-market scan, shortlist two to four candidates that pass your IV and liquidity filters, size each one against your Vega cap, then place limit orders rather than chasing the open.
What post-earnings drift means for options traders and how long it lasts
Immediately after an earnings release, the options market absorbs new information quickly: implied volatility drops, and the bulk of the directional move toward the market's revised view often happens within the first one to two trading sessions. For options positions, this window is the period where both gamma and the IV crush do the most damage or create the most opportunity, depending on which side of the trade you hold.
The practical duration that matters to an options trader is short, typically the session of the print through the next day or two, because that is when open interest, spread width, and realized volatility are still settling into a new normal. Beyond that window, the options chain for the next cycle starts pricing in a fresh baseline rather than reacting to the prior print, which is why exit rules tied to a specific time horizon, not just a price target, belong in every post-earnings plan.

Short-dated options concentrate this effect the most since gamma and time decay compound faster near expiration. A trader holding a position into and through the print should expect the sharpest value changes in the first hours of trading after the announcement, then a decay toward more typical day-to-day volatility as the initial reaction gets digested by the broader market.
Reading post-earnings moves across different market conditions
Measuring how a stock behaves after earnings starts with comparing the realized move to the move the options market had priced in beforehand. If a stock gapped 8% but the straddle only implied a 5% move, that gap represents a surprise the market underestimated, and the options chain typically reprices accordingly in the following sessions.
Market backdrop changes how reliable this read is. In a high-volatility macro environment, broad index moves can mask or exaggerate a single stock's earnings reaction, so comparing the stock's move to its sector or to a relevant index on the same day helps separate earnings-specific drift from market noise. In a calm macro environment, a stock's post-earnings move is more likely to reflect the print itself rather than correlated selling or buying across the market.
Volume and open interest in the days following the print offer another signal. A sustained increase in call or put volume beyond the announcement day, rather than a single spike on the print date itself, often indicates the market is still digesting the news rather than having fully priced it in in a single session. Options-market commentary on trading around economic events notes that heavily traded names concentrate volume around these catalysts, which makes volume patterns in liquid names a cleaner read than in thinly traded stocks where a handful of trades can distort the picture.
Typical risks in post-earnings trades and how to manage them
The most common risk is the IV crush itself: a trader who buys options expecting a big move can be right on direction and still lose money if the volatility component collapses faster than the price gain accrues. Sizing Vega exposure before entry, rather than just capping premium spent, is the most direct way to manage this.
A second risk is gap risk on illiquid names, where a wide bid-ask spread at the open can force a bad fill in either direction. Setting a minimum quote-width requirement and using limit or limit-on-open orders instead of market orders reduces this exposure meaningfully.
A third risk is overconfidence in the expected-move calculation itself. The straddle-implied move is a market estimate, not a guarantee, and a company with pending litigation, regulatory decisions, or guidance changes layered onto its print can move well beyond what the options chain priced in. Position sizing should account for the chance that the actual move exceeds the expected move, not just the chance that it falls short.
A fourth risk is holding a short-vol position through an unexpectedly large gap with insufficient defined risk. Structures like iron condors or credit verticals cap the loss by design, which is one reason defined-risk spreads are generally preferable to naked short options around a known catalyst.
Using earnings surprise and analyst revisions in your trade decisions
An earnings surprise, the gap between reported results and consensus estimates, often drives the initial options reprice more than the raw revenue or earnings-per-share number itself. A company that beats estimates but issues cautious guidance can still see its options chain reprice downward, since the options market is forward-looking and reacts to the full picture, not just the historical quarter.
Analyst estimate revisions in the days following a print add a secondary signal. When multiple analysts raise price targets or earnings estimates after a report, that collective shift often continues to inform options positioning in the following sessions, particularly in how call and put skew adjust. Empirical research on pre-announcement options activity suggests options markets can contain real information ahead of a print, which is a reason to watch options positioning itself, not just analyst notes, as part of your post-earnings read.
Practically, this means checking whether the options chain's implied move already reflects a surprise before you place a post-earnings trade. If a stock beat significantly and analysts are already revising estimates upward, but the options market has not repriced skew to reflect renewed confidence, that gap can be a signal worth incorporating into strike selection, particularly for a directional spread rather than a pure volatility play.
Pre-earnings versus post-earnings IV and what it means for premiums
Implied volatility behaves very differently on the two sides of an earnings print. In the days leading up to the announcement, IV typically climbs steadily as the market prices in event risk, which inflates premiums across the entire chain, calls and puts alike, regardless of which direction the stock eventually moves. This is why buying options in the final day or two before a print is expensive relative to buying the same options weeks earlier.
Once the announcement is public, implied volatility drops sharply, often within minutes of the print or the open of trading. Options education resources describe this as a near-mechanical repricing since the specific uncertainty the options were pricing has now resolved, leaving only the ordinary volatility of the stock going forward.
The practical impact on premiums is significant for anyone holding options through the event. A long option bought the morning of the print carries embedded volatility premium that evaporates almost immediately after the release, meaning the position needs a real directional move just to offset that volatility loss. Conversely, a trader who sold options before the print, assuming they sized the position with defined risk, benefits from that same collapse. This asymmetry is the central reason the strategy choice outlined earlier, short-vol when IV is rich, long-vol when the expected move looks genuinely underpriced, matters more for earnings trades than for ordinary directional positions.

Staying disciplined when the print hits
Our daily protocol is simple: scan before the open, cap total earnings exposure as a fixed share of the account, and reassess at midday once the initial volatility has settled. A rules-based approach, predefined size and predefined exits, keeps a single bad print from becoming a bad month. Discipline, not conviction, is what survives a surprise.
— Customer
Get ranked post-earnings ideas before the open
Finding a vetted earnings trade usually means digging through a chain by hand or guessing at which names actually have a real setup. We built MorningOptions to skip that step: our 5 AI pipeline vets, scores, and delivers ranked, specific contract ideas with entry levels every market morning, built for traders who want a fast, clear read before the bell.
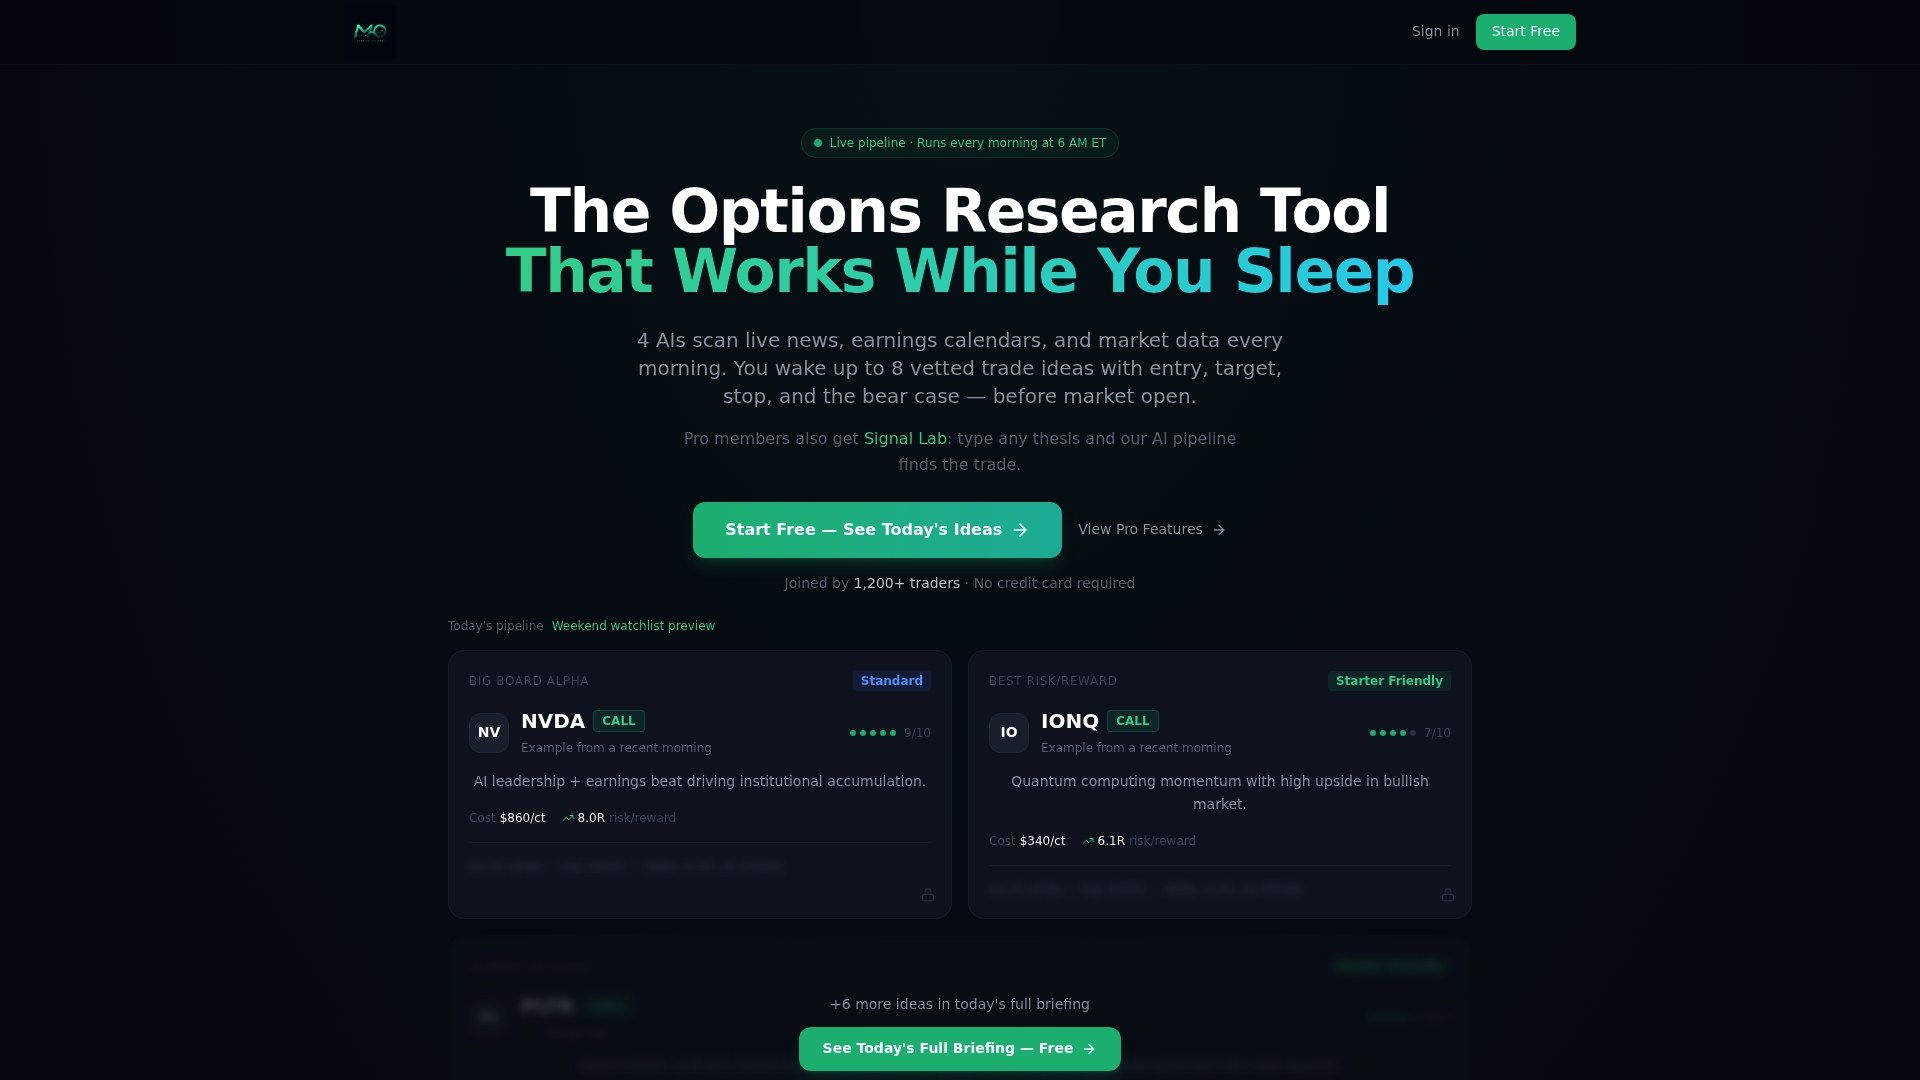
- The free daily briefing gets you ranked contract ideas with entry levels, no guesswork required.
- A paid subscription plan unlocks additional scanning tools and an AI chat scanner for researching any ticker on demand; current prices are on the pricing page.
Start with the free briefing today at Morningoptions and see the next ranked setups before the next print.
FAQ
What is the safest options strategy right after earnings?
Defined-risk spreads, such as credit verticals or iron condors, cap your maximum loss and are generally safer than naked short options when implied volatility is elevated going into a print. The right choice still depends on whether IV looks rich or cheap relative to the expected move, so check that before picking a structure.
How do I calculate the expected move before earnings?
Divide the price of the at-the-money straddle by the stock price for a rough percentage move, or use the heuristic that roughly 16% annualized implied volatility corresponds to about a 1% expected daily move. Multiply that percentage by the stock price to get a dollar estimate.
Why do options lose value even when the stock moves the right way?
This happens because of the IV crush: implied volatility drops sharply after the announcement, and that drop can outweigh the value gained from the directional move, especially for options bought shortly before the print as described in options education resources on IV crush. Checking a position's Vega exposure before entry helps anticipate this effect.
How many days to expiration should I use for an earnings trade?
A common guideline is roughly 3 to 14 days to expiration, which balances enough time value to absorb the move against excessive sensitivity from very short-dated gamma. Shorter expirations amplify both gains and losses from the same price and volatility change.
Does MorningOptions provide post-earnings trade ideas?
Yes, our daily briefings include ranked, specific contract ideas with entry levels generated through a 5 AI pipeline, and the free tier delivers a daily set of ideas at no cost. The Pro tier adds a lunchtime scanner and an AI chat scanner for on-demand research at $89 per month or $742 per year, available at Morningoptions.