Watch delta to pick your strike and gamma to time the entry, then size the trade so a full loss of premium stays inside what you can tolerate. For intraday and 0DTE setups, gamma dominates as expiration nears, so close those positions before the market closes unless you have deliberately planned for overnight risk.
TL;DR:
- For directional scalps, choose delta for desired exposure; higher delta tracks the stock more closely for swings, while lower delta costs less but increases speculation.
- At the money options near expiration have the highest gamma, so small stock moves can sharply change delta and premium; use tighter stops and smaller positions.
- Before a catalyst, elevated implied volatility can fall afterward and hurt long options despite a favorable stock move; consider defined risk spreads instead.
- Size contracts by dividing acceptable dollar loss by premium per contract multiplied by the contract multiplier, then round down using your broker’s specifications.
- Close intraday and same day expiration positions before market close unless you have a specific reason to accept overnight risk.
Table of Contents
- What Each Major Greek Measures
- Using Delta and Gamma to Choose Your Strike and Timing
- Intraday and 0DTE: Gamma Acceleration, Sizing, and Timing
- Pre-Trade Checklist and Entry Rules You Can Copy
- Applying the Greeks in a Daily Trading Workflow
- What Separates Repeatable Entries From Guesswork
- Getting Greek-Informed Entries Before the Open With MorningOptions
- FAQ
- Sources
What Each Major Greek Measures
The commonly used Greeks describe how an option's price may react to changes in market inputs. Learning what each one does, in plain terms, turns Greeks from academic trivia into a decision tool.
Delta estimates how an option's price responds to a move in the underlying stock. Traders also use delta as a rough measure of directional exposure and, with caveats, as an approximate probability of expiring in the money.
Gamma measures how fast delta itself changes as the stock moves. High gamma means delta can swing quickly, which matters most for at-the-money options close to expiration. A trade with low gamma barely changes character as the stock moves a point or two; a trade with high gamma can flip from a modest directional bet to something far more aggressive within minutes.
Theta measures the dollar amount an option loses in value each day, all else equal, purely from the passage of time. Buyers fight theta every day they hold a position, and the bleed accelerates as expiration approaches, which is why a slow, range-bound stock can still cost a buyer money.
Vega measures an option's sensitivity to implied volatility. Vega can matter around catalysts: changing volatility may affect a position even when the stock moves in the expected direction.
Rho measures sensitivity to interest rate changes. Its relevance depends on the option and market conditions, and traders may consider it alongside the other Greeks.
- Delta: directional exposure and rough probability of finishing in the money.
- Gamma: the rate delta accelerates, critical near expiration.
- Theta: daily value lost to time, worse for buyers closer to expiration.
- Vega: sensitivity to implied volatility, decisive around earnings and macro events.
- Rho: sensitivity to interest rate changes.
The Options Industry Council describes these Greeks as working together rather than in isolation: delta behaves like current speed, gamma like acceleration, theta like fuel consumption, and vega like changing weather. Its combined Greeks framework recommends tracking them together rather than fixating on delta alone.
Using Delta and Gamma to Choose Your Strike and Timing
Greeks stop being theory the moment you use them to pick an actual strike and an actual entry moment. The goal is matching the Greek profile to what the trade is supposed to do.
For a quick directional scalp, choose a delta that fits your desired exposure and premium cost. For a swing entry, a higher delta behaves more like the underlying stock, while lower deltas may offer cheaper but more speculative exposure. Assess the trade's risks and potential outcomes before entering.
- Pick the Greek profile to match intent: momentum scalps may favor a delta suited to the desired exposure; swing entries may favor higher deltas; and speculative plays may use lower deltas with full awareness of the risks.
- Prioritize gamma when trading near expiration: at-the-money contracts close to expiry carry the highest gamma, meaning small stock moves produce outsized premium swings, so stops need to be tighter and size needs to be smaller.
- Consider vega ahead of known catalysts: changing implied volatility can affect option prices, so compare the risks of a defined-risk spread with those of an outright long option.
- Weigh theta against structure: compare how time decay may affect a vertical spread with its effect on buying a single option outright. The short leg and long leg can have different theta exposures.
- Set exit rules before entry: choose profit and loss thresholds that fit the strategy, and cap total risk using a max-loss formula.
Pro Tip: Write your target delta, profit target, and stop level on the ticket before you place the trade, not after, so the plan survives the first adrenaline spike.
The max-loss formula keeps sizing tied to your risk limit: max contracts equal your total acceptable dollar loss divided by the premium per contract times the contract multiplier. Use your broker's contract specifications and round down to stay within your loss limit.
Intraday and 0DTE: Gamma Acceleration, Sizing, and Timing
Short-dated and same-day expiration contracts behave differently from anything held for days or weeks, because gamma stops being a background factor and becomes the dominant force in the trade.
As an option approaches expiration, the same one-point move in the underlying stock can produce a dramatically larger swing in both delta and premium than it would a week earlier. An at-the-money 0DTE option might move from 0.50 delta to 0.80 delta on a single sharp one-point push, turning what felt like a moderate directional bet into something closer to owning shares outright, with the premium swings to match. This gamma acceleration near expiration is well documented by options educators and is the primary reason 0DTE trades require tighter risk controls than longer-dated positions.
- Size with the same max-loss formula, but tighten the dollar amount you are willing to risk given how fast gamma can move the premium against you.
- Cap high-gamma trades to a small percentage of total capital, often in the low single digits, since a handful of bad 0DTE entries can erase weeks of gains.
- Choose entry timing deliberately, taking account of changing volume, price action, and the risks of the strategy.
- Assess the risks before entering late in the session, when price moves and liquidity may change unpredictably.
- Close intraday and 0DTE positions before the close unless you have a specific, pre-planned reason to hold overnight risk.
Reading a premarket gamma exposure map, sometimes shown as a GEX chart, before the open gives a sense of where dealer positioning might act as support or resistance, helping frame entries and invalidation points before the first candle prints. Intraday gamma dynamics are not static: a premarket map can change as volume and price action shift, so revisit the levels during the session as well as before the open.
Consider a simple illustration: a trader buys a 0DTE call for $0.50 ($50 total) with delta near 0.45. The same mechanics work in reverse: a move against the position can erase most of that premium within minutes, which is precisely why tight stops and small size matter more here than in any other options setup.

Pre-Trade Checklist and Entry Rules You Can Copy
A repeatable process beats a fresh decision every time you look at a chart. Running through the same checks before every entry removes the guesswork that turns a good setup into an undisciplined trade.
- Call the regime: check whether the market is in a positive or negative gamma environment, since that shapes whether moves tend to get dampened or amplified.
- Pick the delta band: match your target delta to the trade's purpose, whether a scalp, swing, or speculative play, as outlined above.
- Check implied volatility and vega: confirm IV is not unusually inflated ahead of a catalyst unless the strategy is built to handle a volatility crush.
- Confirm with internals: use VWAP, the TICK index, and volume to confirm the move has real participation behind it, not just a thin print.
- Compute position size: apply the max-loss formula before entering, not as an afterthought.
- Set the stop and profit target: define both in terms of price or premium levels, not vague intentions.
The sizing formula uses the contract multiplier: max contracts equal the dollar amount you are willing to lose divided by the premium per contract times that multiplier. Use your broker's contract specifications and round down to keep the position within your predefined loss limit.
Invalidation rules matter as much as entry rules. If the underlying breaks a key level the setup depended on, if volume dries up after entry, or if implied volatility spikes unexpectedly against the position, the trade thesis is broken and the correct action is to exit, not to hope.
A worked example: a trader identifies a positive gamma regime, selects a call, and sets a risk limit. The trader then defines stop and profit-target levels based on the strategy and contract specifications. If the stock moves favorably and the option reaches the target, the trade closes according to plan. For a deeper version of this process, our options entry rules checklist walks through the process in more detail.
Applying the Greeks in a Daily Trading Workflow
The Options Education Institute is explicit that Greeks are theoretical guideposts, not guarantees. Their values are trend-based and can shift sharply around earnings or sudden volatility changes, which means treating any single Greek reading as fixed truth is a mistake traders make often.
- We build each morning briefing around ranked, AI-vetted trade ideas with specific entry levels rather than generic commentary.
- Our briefings surface premarket levels and gamma exposure context so readers can see where Greek-driven risk is concentrated before the open.
- For readers who want to go deeper on the visual side, our options Greeks heatmap post and our gamma exposure calculation guide both expand on the premarket mapping described above.
What Separates Repeatable Entries From Guesswork
The traders who make Greeks work consistently are not the ones with the best theoretical knowledge. They are the ones who journal every entry, track what the Greeks actually did against what they expected, and adjust based on evidence instead of feel.
Sizing limits and stop discipline matter more than any single Greek reading, because a technically perfect entry with no risk control still loses money over time. Before scaling any Greek-based entry rule to real size, test it on a handful of trades at reduced risk and confirm the edge shows up in practice, not just on paper.
— Customer
Getting Greek-Informed Entries Before the Open With MorningOptions
Reading Greeks correctly takes time most active traders do not have before the market opens. Our daily briefings do that work first: we deliver AI-vetted, ranked trade ideas with specific entry levels, premarket context, and gamma exposure indicators built into each setup, so the delta and gamma analysis above is already reflected in the ideas you see.
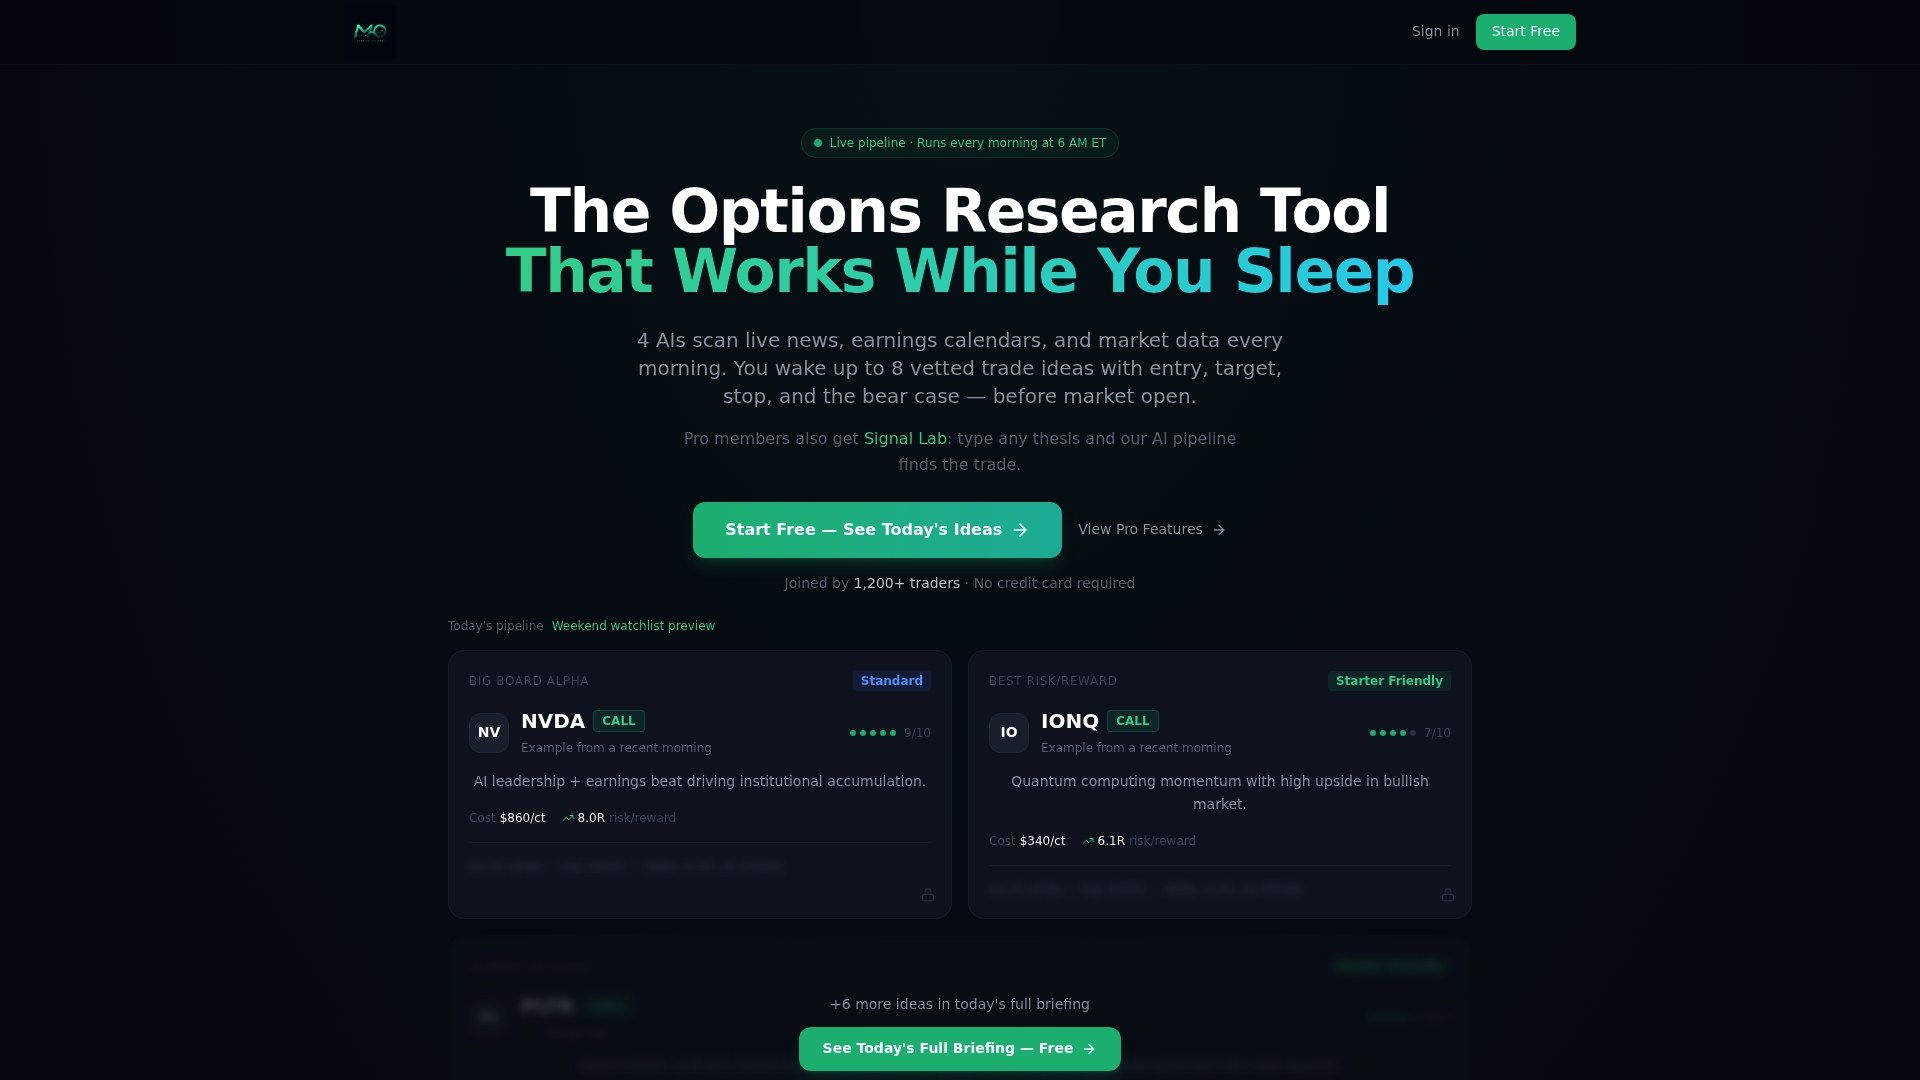
Our free daily briefings cover a limited set of trade ideas each morning, and our Pro plan unlocks the full briefing, the midday scanner, and an on-demand AI chat scanner for researching individual tickers between sessions. Once a Greek-based entry plan is tested and sized the way we outline above, pairing it with ranked ideas from MorningOptions turns the premarket routine into a repeatable morning checklist rather than a scramble. For traders who also want execution automation once a plan is set, a multi-strategy execution approach from a partner platform is worth a look for turning alerts into live orders.
FAQ
What are the five Greeks in options trading?
The five commonly used Greeks are delta, gamma, theta, vega, and rho, each measuring sensitivity to a different input such as stock price, time, or volatility. Delta, gamma, theta, and vega matter most for everyday entries, while rho is a minor factor outside of longer-dated positions.
Why are these risk measures called Greeks?
The terms are called Greeks because most of the symbols used, delta, gamma, theta, vega, and rho, come from or resemble letters in the Greek alphabet, used as shorthand for the underlying calculus behind option pricing. The naming convention stuck because it gives traders a compact vocabulary for describing how an option's price responds to different variables.
What do delta and gamma tell a trader about an entry?
Delta shows how much an option's price should move for a $1 move in the stock and doubles as a rough estimate of directional exposure. Gamma shows how fast that delta itself changes, which is why traders watch gamma closely near expiration when small stock moves can shift an option's behavior quickly.
How should implied volatility change my entry decision?
Elevated implied volatility ahead of a catalyst like earnings inflates vega exposure, and a sharp drop afterward, known as volatility crush, can hurt a position even if the stock moves the right direction. Favoring defined-risk spreads over outright long options ahead of known catalysts reduces that exposure.
Can Greeks guarantee a profitable trade entry?
No single Greek, or combination of Greeks, guarantees an outcome. The Options Education Institute frames Greeks as theoretical guideposts that shift with market conditions, so they inform position sizing and timing rather than promise a result.