Scale the result up or down based on the trade's implied volatility and your confidence in the setup. Regulatory guardrails from FINRA and Regulation T and risk disclosures from the Options Clearing Corporation shape what's actually usable. Pick your percent, run one test trade through the math below, and see where it lands.
TL;DR:
- Position sizing for options should be based on a fixed percentage of account equity, adjusted by a confidence multiplier rather than relying solely on raw calculations.
- Per-contract loss estimates must account for Greeks like theta and vega, especially for short and multi-leg trades, because risks are nonlinear.
- Always round down the number of contracts after dividing the risk budget by per-contract loss to avoid oversizing and account for commissions and slippage.
- Margin requirements and broker-specific rules significantly influence the feasible trade size, especially for short options, so stress testing potential margin calls is essential.
- Combining AI-ranked trade ideas with predefined risk parameters and a disciplined workflow helps maintain consistent position sizes and manage overall portfolio risk.
Table of Contents
- Core position sizing methods for options traders
- How to calculate position size for options: step-by-step and formulas
- Worked examples: small account and larger account calculations
- Account-level constraints and margin considerations that affect sizing
- Risk controls and operational rules to preserve capital
- Applying these methods in practice: how AI scoring and confidence-weighting change sizing
- Adjusting position size for different options strategies
- The role of time decay in sizing decisions
- Position sizing for directional vs. non-directional option trades
- Author perspective: why sizing beats picking perfect entries
- How MorningOptions helps you set and apply position sizing in your daily workflow
- Sources
- FAQ
Core position sizing methods for options traders
Most options traders rely on a handful of sizing frameworks, each suited to a different risk appetite and account structure.
Fixed-fractional sizing risks a constant percentage of current equity on each trade. The formula is simple: position size equals account equity multiplied by risk percent, divided by per-contract loss. It adjusts naturally as your account grows or shrinks, which keeps losing streaks from compounding into account-ending drawdowns.
Volatility targeting scales position size inversely to a security's recent volatility, so a wild biotech stock gets a smaller allocation than a steady index fund for the same dollar risk. This method keeps portfolio swings roughly consistent across changing market regimes rather than letting a few volatile names dominate your risk.
Kelly and fractional Kelly calculate the mathematically optimal bet size based on your edge and win rate. Full Kelly is aggressive and sensitive to estimation error, so most practitioners use a quarter or half Kelly as a practical ceiling rather than a target. Position sizing research treats fractional Kelly as a theoretical upper bound, with fixed-fractional and volatility targeting serving as the everyday baselines.
Options complicate all three methods because risk isn't linear; understanding key factors like theta, vega, and delta is essential for accurate per-contract loss estimates as explained in Options greeks explained. A long call can lose most of its value from time decay alone, with no movement in the underlying stock, so per-contract loss needs to reflect theta and vega exposure, not just the distance from entry to a stop price.
- Fixed-fractional: steady, equity-based, easiest to apply consistently.
- Volatility targeting: adjusts for how wild the underlying actually trades.
- Fractional Kelly: a ceiling for growth, not a daily sizing rule.
Pro Tip: Run your baseline fixed-fractional number first, then check it against a quarter-Kelly estimate. If fixed-fractional comes in smaller, use it. If Kelly comes in smaller, that's your signal the trade's edge doesn't justify a bigger bet.
How to calculate position size for options: step-by-step and formulas
The calculation flow stays the same whether you're trading a single call or a four-leg spread.
- Set your risk percent. Choose a fixed percentage of account equity, typically 0.5% to 1% per trade.
- Compute your dollar risk budget. Multiply account equity by that percent.
- Estimate per-contract loss. For a long option, this is the premium you'd lose if your stop triggers or the position goes to zero. For a defined-risk spread, it's the max loss stated in the trade. For a short, undefined-risk option, model a stress scenario, not just the credit received.
- Divide and round down. Dollar risk budget divided by per-contract loss gives your contract count. Always round down to the nearest whole contract.
Position size = (Account equity × Risk percent) / Per-contract loss, with a confidence multiplier applied afterward. That relationship comes directly from position sizing logic that treats confidence as a multiplier layered on top of the baseline calculation.
Commissions and slippage eat into the math on both ends: they raise your effective per-contract loss and shrink the profit side of the trade.
For spreads specifically, per-contract worst-case loss is the defined max loss of the structure, not the premium paid, since the short leg changes the payoff profile entirely. Research on sizing notes that multi-leg trades require this distinction because premium paid understates real risk once both legs are accounted for.
Worked examples: small account and larger account calculations
Numbers make the formula concrete.
A long call entered at $2.00 with a stop where premium falls to $0.50 risks $1.50 per share, or $150 per contract. Since $100 divided by $150 rounds down to zero, this trader either lowers the stop distance, picks a cheaper contract, or skips the trade rather than oversize it.
A short credit spread with a defined max loss of $400 per contract allows $500 divided by $400, which rounds down to one contract, leaving a small buffer against commissions.
- Always round down, never up, when the division produces a fraction.
- Undersizing when margin or assignment risk is uncertain is the conservative, correct choice.
- A $0 result is useful information: it tells you the trade doesn't fit your risk budget as structured.
Account-level constraints and margin considerations that affect sizing
Your sizing math only matters if your broker will actually let you place the trade. Regulation T and FINRA rules set a minimum maintenance margin of 25%, though many brokers require 30% to 40% in practice, and brokers must approve your account for specific options trading levels before you can sell spreads or naked options.
Buying options ties up only the premium paid, a known, capped cost. Selling options is different: margin requirements scale with potential loss, and margining mechanics differ between equity-style and futures-style contracts, affecting how much collateral a short position actually consumes.
- Check your broker's specific maintenance margin before assuming the FINRA minimum applies.
- Size short options smaller than long options of equivalent premium, since assignment or a gap move can produce losses the credit received never covered.
- Simulate a worst-case margin call before allocating to a short strategy, not after.
Risk controls and operational rules to preserve capital
A sizing formula only protects you if it's backed by rules that prevent one bad week from becoming a bad year.
- Cap individual trade risk at 1% to 3% of equity, tightening toward the low end for high-frequency or highly leveraged strategies.
- Set a portfolio heat limit, for example capping total at-risk capital across correlated positions (several tech calls, say) at 5% to 6% combined.
- Reduce size heading into earnings or other binary catalysts, since implied volatility often collapses right after the event regardless of direction.
- Keep a cash or low-risk buffer for overnight gap risk, especially on short option positions that can't be closed before a surprise move.
Pro Tip: Before entering any trade, run a three-line check: equity times risk percent, divided by per-contract loss, confirmed against your current portfolio heat. If either the math or the heat limit fails, skip the trade.
Applying these methods in practice: how AI scoring and confidence-weighting change sizing
Confidence-weighting takes your baseline contract count and multiplies it by a factor reflecting how strong the setup looks, capped well below your maximum per-trade risk. A score-based multiplier might range from 0.5 for a marginal setup to 1.5 for a high-conviction one, never higher.
Calibration matters more than the multiplier itself: back-test any scoring system against historical trades, check it holds up walk-forward on data it hasn't seen, and set a hard ceiling so no single score pushes you past your portfolio heat limit.
- Ranked, pre-market briefings give a starting confidence read before you apply your own multiplier.
- Entry and exit levels attached to an idea simplify estimating per-contract loss for the formula above.
- An on-demand scanner for researching tickers helps verify a setup before sizing it up.
Adjusting position size for different options strategies
A single long call, a credit spread, and a straddle each demand a different approach to the same formula.

Single-leg long options (calls or puts) have premium paid as the natural ceiling for per-contract loss, since the position can't lose more than what you put in. This makes sizing straightforward but requires accounting for how fast that premium can erode from time decay alone.
Defined-risk spreads (verticals, iron condors) use the spread's max loss, which is fixed at entry and doesn't change with assignment risk the way a single short option does. This generally allows for slightly larger position counts relative to premium at risk, since the downside is capped by design.
Straddles and strangles combine two long legs, so total premium at risk is the sum of both, and per-contract loss should reflect that combined cost along with the fact that one side will likely decay to zero even if the trade works. Sizing a straddle off just one leg's premium understates total capital at risk.
Short, undefined-risk positions (naked calls or puts) require a stress-scenario estimate rather than the credit received, since a large adverse move can produce losses many multiples of the premium collected. This is the category where undersizing relative to the formula's raw output is most justified.
The role of time decay in sizing decisions
Theta erodes an option's value every day that passes, independent of what the underlying stock does, and that steady bleed needs to factor into how much you risk per trade. A long option close to expiration can lose a meaningful chunk of its remaining value in a single session purely from time decay, which means the effective per-contract loss used in your sizing formula should reflect a stress scenario that includes theta, not just a price-based stop.
Research on position sizing for options points out that these non-linear risks, theta and vega together, mean a contract can lose real value without any move in the underlying at all. That's a different risk profile than a stock position, where the loss is tied directly to price movement.
Shorter-dated options carry faster theta decay, which argues for smaller size or a shorter holding window relative to expiration. Longer-dated options decay more slowly but tie up capital longer, which affects how many other positions your portfolio heat limit allows at the same time. Either way, the per-contract loss estimate in your formula should account for how many days you actually plan to hold the position, not just the full premium paid.
Position sizing for directional vs. non-directional option trades
A directional trade, a long call or put betting on price movement, sizes primarily off the premium at risk and the conviction behind the directional view. Since the entire position depends on getting the direction right, sizing tends to be more conservative per trade, with confidence-weighting playing a larger role since a wrong directional call offers no partial credit.
Non-directional trades, like iron condors or calendar spreads that profit from time decay or volatility contraction regardless of price direction, carry a different risk shape. The max loss is usually defined at entry, which allows for sizing based on that fixed number rather than a volatility-adjusted stop. These trades can often tolerate a slightly larger position per unit of defined risk, since the win rate tends to be higher even though individual losses can be sharper when they occur.
The practical difference comes down to what you're measuring: directional trades size against a price-based loss scenario, while non-directional trades size against a defined structural max loss. Mixing the two frameworks, treating a condor's defined risk like a directional stop, or vice versa, is a common sizing mistake that either overexposes or unnecessarily shrinks a position relative to its actual risk.

Author perspective: why sizing beats picking perfect entries
Years of watching retail accounts blow up taught me the same lesson every time: it was never the entry that killed the account, it was the size. A trader with mediocre entries and strict sizing discipline outlasts one with great entries and no sizing rules. The accounts that survived long drawdowns weren't the ones that called the bottom, they were the ones that never risked enough on any single idea to need to.
— Customer
How MorningOptions helps you set and apply position sizing in your daily workflow
Once your sizing formula is set, the harder part is doing it consistently every morning before the open. MorningOptions delivers ranked, AI-vetted trade ideas with entry and exit levels built in, which gives you the per-contract loss estimate you need for the formula without digging through an options chain yourself.
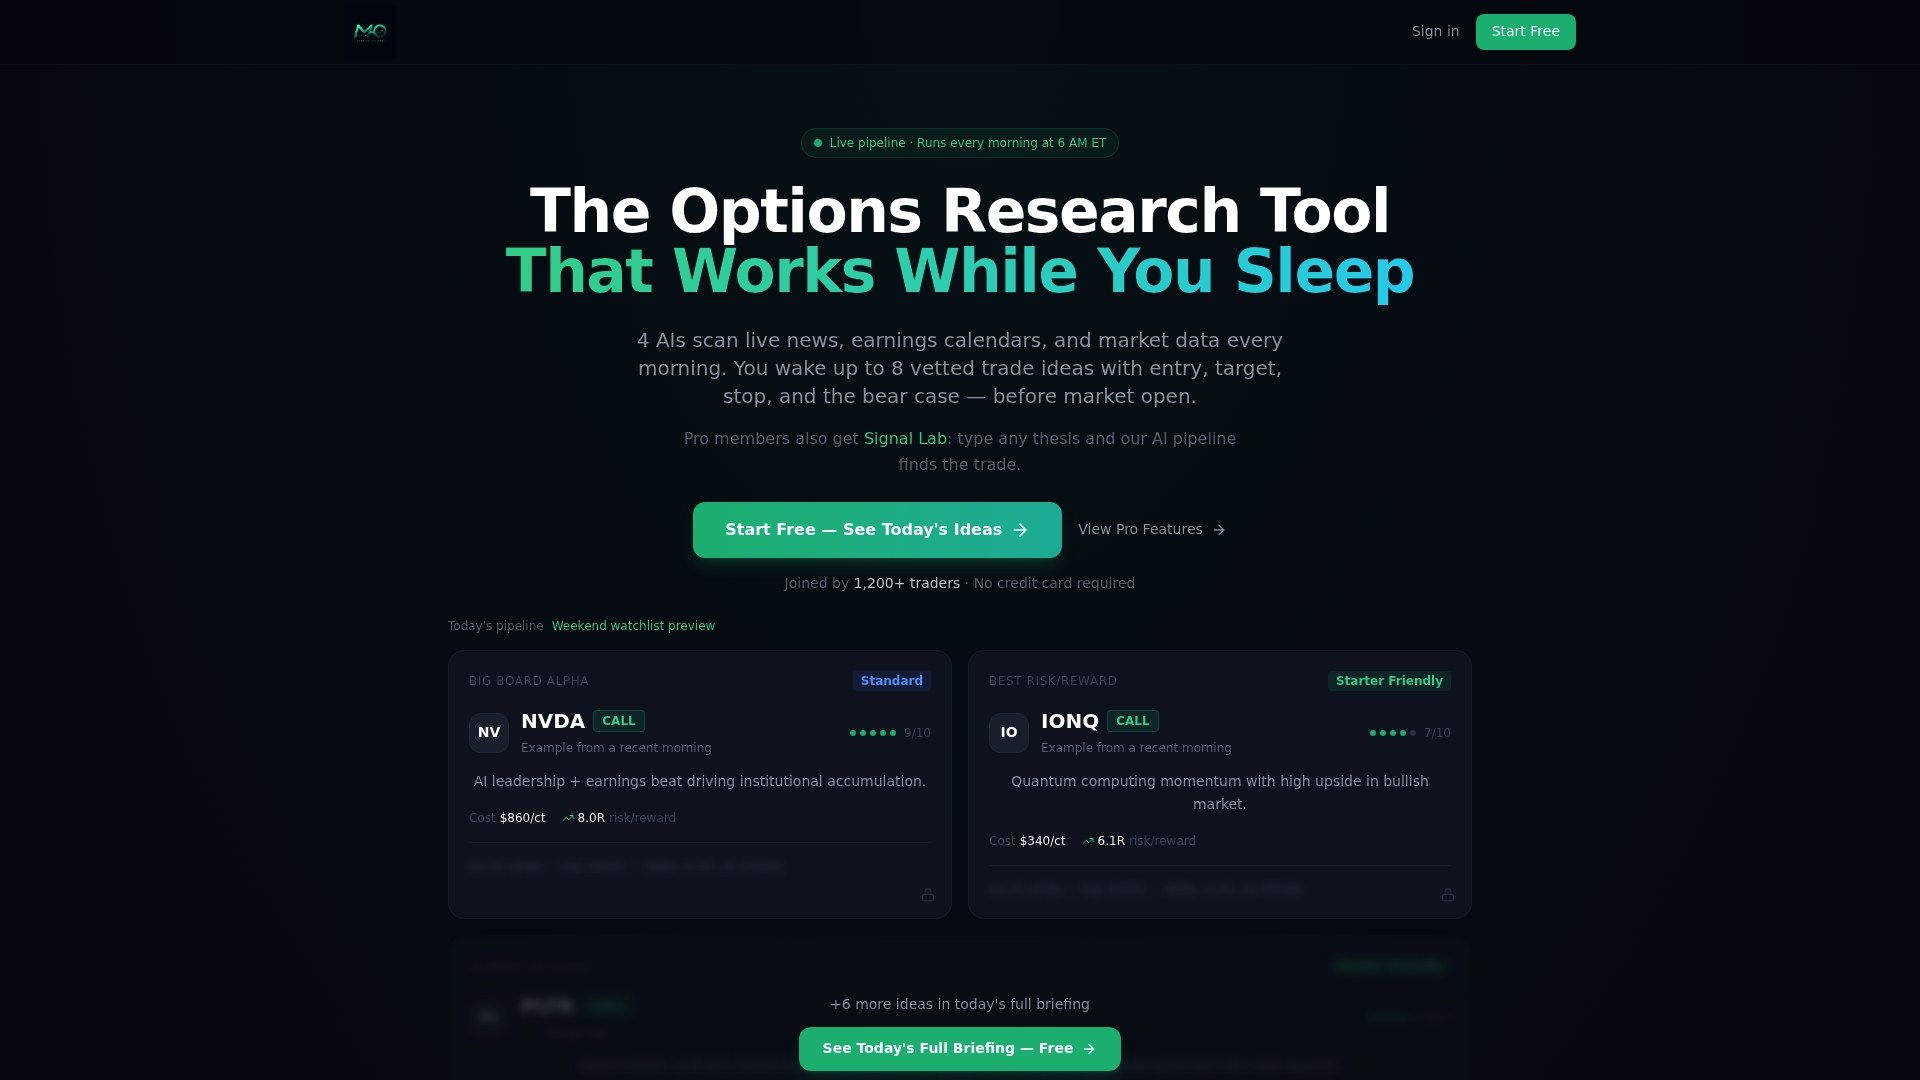
A simple workflow: read the morning briefing, compute your baseline contract count from your risk budget, apply a confidence multiplier based on how the idea ranked, then place a conservative order rounded down. The free plan covers daily briefings, while Pro at $89 per month unlocks the lunchtime scanner and an AI chat scanner, Signal Lab, for researching tickers on demand between the open and close.
- Ranked pre-market briefings with entry and exit levels attached to each idea.
- Signal Lab for on-demand scans when a midday setup needs a second look.
- A workflow built around the same sizing math covered above, not vague commentary.
Set your risk percent today, then see how a ranked idea fits into it at Morningoptions.
Sources
The margin and risk figures referenced throughout this article come from regulatory and research sources worth reading directly.
- Investor
- Position Sizing Logic — AICELS
- A primer on margining styles for options - CME Group
- The Power of Position Sizing in Portfolio Management
FAQ
What is the 3-5-7 rule in options trading?
It's not a regulatory standard, just a widely cited heuristic that functions similarly to the portfolio heat limits described above.
What is the 3-5-7 rule in investing?
The exact percentages vary by source, so treat it as a starting guideline rather than a fixed rule.
How do I do position sizing for an options trade?
Adjust the result based on the option's implied volatility and your confidence in the setup before placing the order.
What are Van Tharp's position sizing strategies?
Van Tharp's approach centers on sizing trades as a function of account equity and a trade's R-multiple, the ratio of potential loss to the amount risked, rather than a fixed number of shares or contracts. His models emphasize matching position size to both account goals and the specific risk of each setup, a framework consistent with the fixed-fractional and volatility-adjusted methods covered in this article.
Why does per-contract loss matter more than stock price for options?
Per-contract loss accounts for time decay and volatility changes that can erode an option's value even without an adverse price move, which a simple stock-style stop distance misses. Estimating loss through a stress scenario, especially for short or multi-leg positions, gives a more accurate number to divide into your risk budget.