Vanna and charm are second-order Greeks that move dealer hedges, vanna through shifts in implied volatility and charm through the simple passage of time, and those hedges can create mechanical buying or selling even on a flat tape. Vanna explains why markets often rally after volatility collapses. Charm explains why price tends to drift in a set direction as expiration approaches. Neither requires news. Both show up in the tape whether you're watching for them or not.
TL;DR:
- Vanna is most impactful during sharp implied volatility drops, forcing dealers to rebalance and often triggering rally-like moves regardless of news.
- Charm accelerates dramatically in the final days or hours before expiration, especially in 0DTE contracts, influencing hedging behavior.
- Dealer hedging reacts differently depending on whether they are net short or long gamma, causing opposite price effects during volatility shifts.
- Accurate exposure estimates require full chain data and open interest concentration, but proxies like VIX and composite metrics can guide interpretation.
- Combining gamma, vanna, and charm insights with broader market context improves timing and risk management for options trades.
Table of Contents
- What Vanna and Charm Actually Measure
- Where Vanna and Charm Sit Next to Gamma, Vega, and Theta
- The Hedging Chain: From Greek Change to Real Trades
- Reading Real Sessions: Post-Event, OPEX, and 0DTE
- How to Estimate Vanna and Charm Exposure
- Putting Vanna and Charm Into Your Trading
- How Morningoptions Helps You Track Exposure Context
- When Second-Order Greeks Actually Matter
- Get Pre-Market Briefings Built Around Exposure Context
- Sources
- FAQ
What Vanna and Charm Actually Measure
Vanna is the rate of change in an option's delta relative to a change in implied volatility, written as ∂Δ/∂σ. It's mathematically identical to ∂Vega/∂Spot, which is why traders sometimes describe it as "how vega bleeds into delta." When implied volatility drops sharply, out-of-the-money options lose delta exposure fast, forcing dealers who are short those options to rebalance.
Charm is the rate of change in delta with respect to time, ∂Δ/∂t. Some call it "delta decay," and the name fits: as expiration nears, an option's delta migrates toward 0 or 1 depending on moneyness, even if the underlying hasn't moved a cent.
Vanna behaves differently across the strike chain. At-the-money options show the least vanna sensitivity; far out-of-the-money or deep in-the-money contracts show more, and the effect compounds as implied volatility itself becomes more elevated. Charm, meanwhile, is roughly negligible with months to expiration and accelerates hard in the final week, then again in the final hours of a 0DTE session.
Where Vanna and Charm Sit Next to Gamma, Vega, and Theta
Gamma reacts to spot price movement. Vanna reacts to volatility movement. Charm reacts to nothing but the clock. That's the entire hierarchy in one sentence, but it matters for how you read a session.
Gamma dominates when spot is moving and dealers are chasing delta in a straight line. Vanna dominates when spot is quiet but implied volatility is repricing hard, the classic post-event scenario. Charm dominates in the final days or hours before expiration, when time decay on delta itself becomes the primary driver of hedge flow regardless of what spot or volatility are doing.
The practical order of operations: read gamma first to understand the dealer book's directional posture, then layer in vanna and charm to explain the moves gamma alone can't account for.

The Hedging Chain: From Greek Change to Real Trades
Dealers who sell options run short gamma, short vanna, and short charm books in aggregate, which means they hedge in the opposite direction of the retail flow they absorbed. When implied volatility drops after an event, vanna forces those dealers to buy back deltas they were short, and that buying shows up as sustained, low-volatility grinding in the underlying or its futures. When implied volatility spikes, the reverse happens: vanna-driven selling adds pressure to an already falling market.
Charm's mechanics run on a separate clock. As options march toward expiration, deltas on the dealer's book shift predictably, and dealers rebalance in the same direction every day that positioning stays roughly static. That's the source of the steady, low-drama grind so many traders notice in the days before a large monthly options expiration.
The hedge chain works like this:
- A shift in IV or the passage of time changes the modeled delta of thousands of contracts simultaneously.
- Dealers, whose net position is the mirror image of what they sold, must trade the underlying or its futures to stay delta-neutral.
- That rebalancing becomes real order flow, buying or selling that has nothing to do with anyone's view on the stock.
- The direction and size of that flow depends on whether dealers are net short or net long gamma, which flips the sign of the vanna and charm effect entirely.
That last point is the one traders miss most often. The same vanna reading can produce opposite price reactions depending on the prevailing gamma exposure regime. Positive gamma dampens moves; negative gamma amplifies them.
Reading Real Sessions: Post-Event, OPEX, and 0DTE
The clearest vanna setup is the post-catalyst volatility crush. Here's how it typically unfolds:
- Ahead of an earnings report or Fed decision, implied volatility climbs as traders buy protection and dealers end up net short puts and calls across the chain.
- The event passes, uncertainty resolves, and implied volatility collapses within minutes.
- That IV collapse mechanically shrinks the delta on the options dealers are short, forcing them to buy back underlying or futures to stay hedged.
- The result is a grinding rally that has little to do with the actual news and everything to do with vol-compression hedging.
Charm follows a slower but equally mechanical script during options expiration week, then compresses into hours during 0DTE sessions. The rise of same-day expiration contracts has made charm's intraday role far more visible than it used to be, since a huge share of notional exposure now expires within the trading day rather than weeks out.
Vanna and charm sometimes reinforce each other, like the final session before a monthly expiration when falling IV and accelerating time decay both push dealers to buy. They also conflict: a sudden spot move can override both, since gamma-driven hedging happens faster and in larger size than either second-order effect.
How to Estimate Vanna and Charm Exposure
Getting a usable exposure read starts with data most retail platforms don't expose cleanly: a full options chain snapshot, per-strike implied volatility, open interest at every strike, and enough underlying or futures liquidity data to judge how easily dealers can actually execute their hedges.
The computation itself involves calculating ∂Δ/∂σ and ∂Δ/∂t at each strike and expiry, then aggregating across the chain using assumptions about which side of the trade dealers are on. That last part is where every estimate gets shaky, since actual dealer positioning isn't public data.
Traders lean on proxies instead:
- VIX direction as a rough stand-in for the vanna-driving IV move.
- Front-month open interest concentration to flag where charm risk is heaviest.
- Composite exposure metrics, sometimes labeled GEX, VEX, or CHEX, that bundle gamma, vanna, and charm into a single dealer-positioning estimate.
Pro Tip: Treat any single vendor's exposure chart as one opinion, not a fact. Because positioning assumptions vary, different vendors can show conflicting vanna and charm readings for the same session, so cross-check with price action before sizing a trade around it.
Vendor disagreement isn't a flaw to work around, it's baked into the math. Every model is guessing at dealer inventory that no one outside the dealer desk actually sees.
Putting Vanna and Charm Into Your Trading
Vanna readings are most useful around known catalysts. If implied volatility is elevated heading into an earnings date or Fed meeting, a post-event vanna bid is a reasonable base case to plan around, not a guarantee. That context can help you decide whether to hold a long-vega position into the print or take profits before the crush erases your edge.
Charm context matters most in expiration week. If you're sizing an intraday 0DTE trade, knowing that charm accelerates hard in the final two hours changes how you think about stop placement and how much conviction to put behind a fade against the prevailing drift.
Layer these reads on top of gamma, never in place of it. A short checklist before treating either as a signal: is gamma exposure large enough at current spot to matter, is open interest concentrated enough to move the aggregate number, and is the IV move you're seeing broad-based or isolated to one name. Skip any setup where you can't answer all three with confidence.
How Morningoptions Helps You Track Exposure Context
The platform runs an AI pipeline that vets and scores options ideas every trading morning, processing full chain data alongside news and earnings catalysts to build each briefing. That chain-level processing gives you a pre-market reference point for cross-checking your own vanna and charm reads against the ideas the platform surfaces. Use it alongside your own chain analysis rather than as a replacement for it, especially heading into expiration-heavy sessions.
When Second-Order Greeks Actually Matter
Gamma tells you the story first. Vanna and charm only refine it, they don't replace it.
Before trusting a vanna or charm read, check three things fast: is implied volatility actually moving or just chopping, is open interest concentrated enough at nearby strikes to matter, and is expiration close enough that charm even has room to accelerate. If IV is flat and OI is thin, you're looking at noise dressed up as signal. Save your attention for the sessions where all three line up.
— Customer
Get Pre-Market Briefings Built Around Exposure Context
The platform gives you daily briefings with ranked, specific contract ideas, entry levels included, instead of vague market commentary you have to interpret yourself. The free plan delivers a daily briefing every trading morning; the Pro plan at $89 per month unlocks the lunchtime scanner and an on-demand AI chat scanner (Signal Lab) for researching any ticker against the same exposure and catalyst context covered in this article.
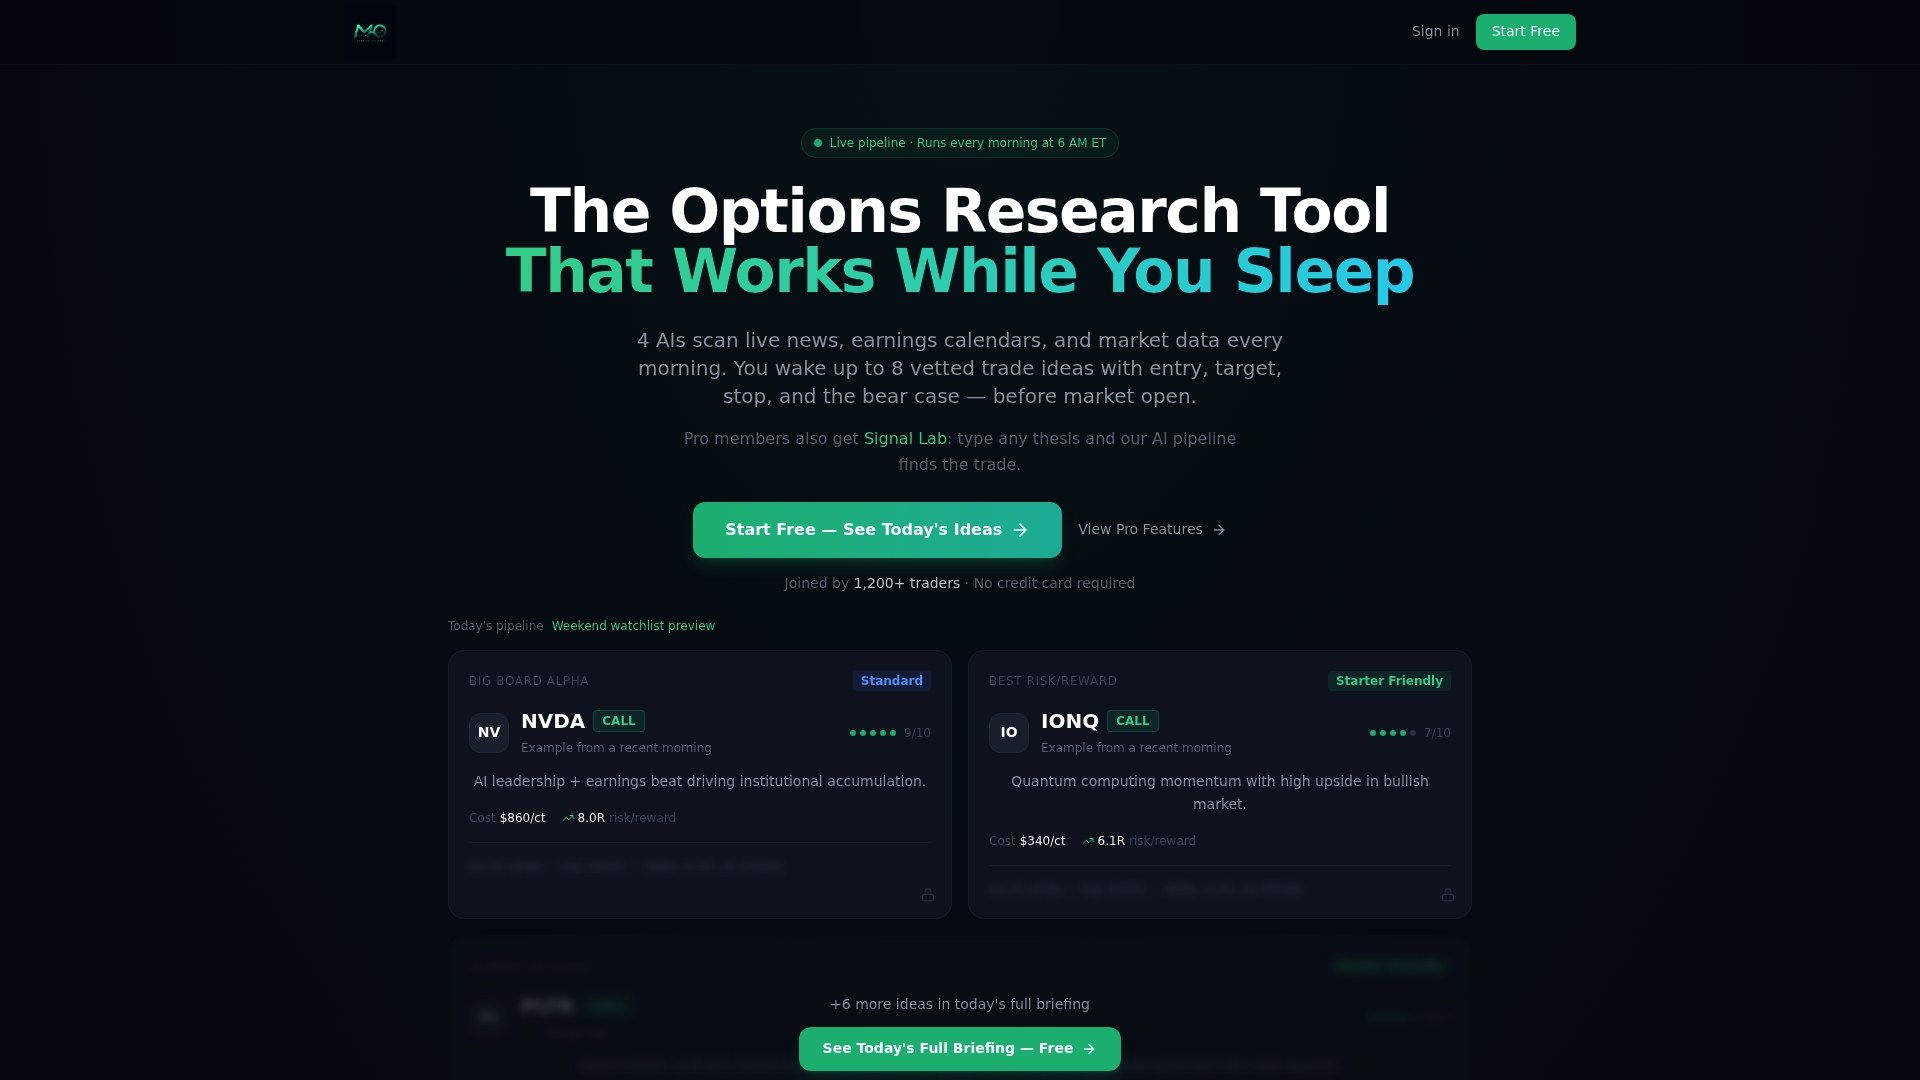
If you're already tracking vanna and charm setups manually, pair that work with a briefing built from full chain data and catalyst scans before the open. Head to the Morningoptions site to see the current day's free briefing and decide from there whether Signal Lab's on-demand scans fit your pre-market routine.
Sources
- Vanna and Charm Effects on Options: How Volatility and Time Drive Hedging Flows | TradeGEX Academy
- Vanna and Charm Explained — Dealer Hedging Greeks
- Vanna & Charm: The Greeks That Move Markets | FlashAlpha
- Charm definition — Investopedia
FAQ
What's the Difference Between Gamma and Vanna?
Gamma measures how delta changes when the underlying price moves; vanna measures how delta changes when implied volatility moves. Gamma dominates during sharp spot moves, while vanna dominates when implied volatility is repricing on a relatively quiet tape.
What Is Charm in Options Trading?
Charm is the rate at which an option's delta changes purely from the passage of time, sometimes called delta decay. It's negligible with months to expiration and accelerates sharply in the final days or hours before expiry, especially in 0DTE contracts.
Is the V Pattern Bullish?
A "V" shaped price recovery after a sharp drop is often bullish in practice, particularly when it coincides with an implied volatility crush that triggers vanna-driven dealer buying. It's a pattern worth watching for, not a guaranteed reversal signal on its own.
What Does a High Vega Signify?
High vega means an option's price is highly sensitive to changes in implied volatility, so even a small IV move produces a large price swing in that contract. Positions with high aggregate vega across a dealer's book are also where vanna effects tend to be strongest, since vanna is essentially vega's sensitivity to spot.
How Does Morningoptions Factor Exposure Context Into Its Briefings?
Morningoptions processes full options chain data, per-strike Greeks, and news and earnings catalysts through a five-step AI pipeline before each trading day's briefing. The free plan includes a daily briefing, while the Pro plan adds a lunchtime scanner and on-demand chat scanner for deeper, ticker-specific research.