Pin risk is the uncertainty an options seller faces when the underlying stock closes at or very near the strike price on expiration day. You don't know whether your short option will be assigned, so you don't know whether you'll wake up Monday holding a stock position you never planned. The fix is almost always the same: decide before the closing bell, not after it.
This guide explains how pin risk works, why stocks sometimes gravitate toward a strike, how it differs from early assignment and early exercise risk, and a practical routine for expiration week.
TL;DR
- Pin risk is not knowing whether a short option near the money will be exercised, which can leave you with an unwanted long or short stock position after the close.
- U.S. listed equity options that finish at least $0.01 in the money are automatically exercised unless the holder gives contrary instructions through a broker.
- Spreads are exposed too: if one leg is assigned and the other isn't, you can end up unhedged over the weekend.
- Early assignment is a separate risk that can hit any time before expiration, often around ex-dividend dates.
- The cleanest defense is a written exit rule: close or roll near-the-money shorts before your broker's cut-off, not at the last minute.
Table of Contents
- What pin risk means in plain terms
- Why the holder's choice is hard to predict
- Who is exposed
- Early assignment and early exercise risk
- How to manage pin risk before expiration
- Our perspective
- Put a plan around your next expiration
- FAQ
- Sources
What pin risk means in plain terms
An option seller takes on an obligation. If you sold a call, you may have to deliver 100 shares at the strike. If you sold a put, you may have to buy 100 shares at the strike. Normally, expiration is simple. An option far out of the money expires worthless, and one deep in the money is clearly going to be exercised.
Pin risk lives in the gray zone in between. According to Investopedia, it is the uncertainty traders face when the underlying closes very near the strike at expiration, leaving them unsure whether their options will be exercised or assigned. If the stock settles at $50.02 and you sold the $50 put, that put is out of the money, and it is probably safe. If it settles at $49.99, it is in the money and is likely to be exercised. A two-cent difference decides whether you buy 100 shares.
The real problem is timing. Exercise decisions are made after the market closes, and you find out what happened afterward. The same Investopedia explanation notes that an unhedged position can face adverse price gaps before trading resumes. In other words, you can own or owe stock while the market is closed, and the next open may not be friendly.

A worked example
Say you sold a $100 put on a stock as part of a short-term income trade. On expiration Friday, the stock closes at $99.97. The put is $0.03 in the money. Whether it is exercised is not your decision, and it isn't certain.
- If it is exercised, you are assigned and now own 100 shares at $100 per share. That is $10,000 of exposure you may not have planned for, and the stock could gap lower Monday.
- If it isn't, the put expires and you keep the premium.
This is an illustration with made-up numbers, but the structure is real. The risk isn't the $0.03. It is the weekend position that appears or doesn't appear, depending on a decision you can't see.
Why the holder's choice is hard to predict
It feels like a deep-in-the-money option is automatically exercised and everything else expires. That's mostly true, but the edges are fuzzy.
Under the Options Clearing Corporation's exercise-by-exception process, listed equity options that are at least $0.01 in the money are automatically exercised unless the holder submits contrary exercise instructions through their broker. So a penny in the money usually means exercise, and a holder who doesn't want it has to act.
That last part is where predictions break down. Holders can submit contrary instructions, and brokers may set their own deadlines. According to a comment letter on FINRA's complex products rules, members may set earlier cut-off times for customers to submit exercise instructions, and FINRA Rule 2360(b)(23) allowed that as of 2022. The 5:30 p.m. ET window many traders have in their heads is not necessarily the one their own broker uses. We cover this in more detail in our guide to options expiration rules and cut-off times.
A holder might also decide an option that is slightly in the money is not worth exercising. Exercise can carry brokerage fees, and for a tiny gain that cost can make exercising irrational. A long holder who looks at the numbers might tell the broker not to exercise. You can't see any of this from the outside, so you can't count on it.

Why stocks sometimes seem to gravitate to strikes
Traders also talk about stocks being "pinned" to a strike. Investopedia's explanation of pinning the strike describes one mechanism: as expiration approaches, the gamma of options rises, so traders trying to stay delta-neutral have to buy or sell larger amounts of the underlying as the price moves. That hedging can itself help hold the stock near a strike.
Investopedia's pin risk page also notes that some market participants may try to nudge a stock toward a particular strike as expiration nears, to influence whether contracts are exercised or expire worthless. Whether any given pin is hedging flow or something else, you don't need to settle that question to act on it. What matters is the practical signal: a heavy cluster of open interest at a strike near the current price is a warning that expiration day may be choppy around that level.
You can read open interest and volume at specific strikes to see where that cluster sits. A primer on volume and open interest signals shows how to read those numbers in context, and the same habit applies to listed options on any ticker you trade.
Who is exposed
Pin risk is mainly a seller's problem, but not only a seller's.
- Short single options. Covered calls, cash-secured puts and naked shorts all carry the "will I or won't I be assigned" question when the stock sits at the strike.
- Spreads and other multi-leg trades. This is the one people underestimate. The comment letter above explains that holding a multi-leg strategy through expiration is risky because you may not know whether a specific leg will be assigned until the following business day, which can leave one side unhedged. A vertical spread is supposed to cap your risk, but a short leg that is assigned while the long leg isn't exercised leaves you with a naked stock position.
- Long holders. If you are long an option that is barely in the money, you could be exercised into stock you didn't want, or fail to exercise something that would have been profitable. Either outcome can be avoided by deciding ahead of time.
Pin risk versus assignment risk versus early exercise risk
These three terms are easy to blur, so here is how they separate.
| Risk | When it happens | Who it hits | Typical trigger |
|---|---|---|---|
| Pin risk | At expiration | Short option holders, spread traders | Stock closes at or near the strike |
| Early assignment risk | Any time before expiration (American-style options) | Option writers | Holder exercises early |
| Early exercise risk | Any time before expiration | The holder's decision, felt by the writer | Dividend capture, hard-to-borrow stock |
The first is about uncertainty at the finish line. The second and third are two sides of the same event: a holder exercises early, and the writer is assigned.
Early assignment and early exercise risk
Early assignment risk is the chance that the writer of an American-style option is assigned to fulfill the contract at any time before expiration. According to Interactive Brokers' Traders' Academy lesson on exercise and assignment, this typically happens when the holder finds it advantageous to exercise early, for example to capture a pending dividend or to cover a short position when shares are hard to borrow. When you are assigned, you must deliver or buy 100 shares at the strike, regardless of where the stock trades.
Seen from the holder's side, that is early exercise risk: the chance that the holder exercises before expiration, which generally gives up the option's remaining time value. The same lesson says a holder might do it when the stock is going ex-dividend or when it is hard to borrow.
FINRA's investor guidance on assignment adds another trigger: a long holder may exercise early after a significant price move, or when shares become hard to borrow because of a pending corporate action such as a buyout or takeover.
Two practical takeaways follow.
- Dividends matter for short calls. A short in-the-money call going into an ex-dividend date is a classic setup for early assignment. We lay out a checklist in 4 checks to avoid assignment on ex-dividend options.
- Corporate actions change the math. If a takeover is announced, the usual patterns for exercise can shift. Read the news before you hold a short option through it.
For the mechanics of what happens after you are assigned, see our retail trader's guide to options assignment.
How to manage pin risk before expiration
The goal is simple: don't carry a coin-flip into a closed market. Here's a routine that does that.
1. Know your broker's cut-off, not the textbook one
Find your broker's deadline for exercise instructions and for submitting contrary instructions. Because members may set cut-offs earlier than the standard window, as covered above, this is a lookup you do once and write down. Put it in your trading notes so it isn't something you try to remember at 3:55 p.m.
2. Mark your near-the-money shorts early in expiration week
On Monday or Tuesday of expiration week, list every short option whose strike is within a small distance of the current price. Decide what "small" means for you. For a $400 stock, a few dollars might matter. For a $20 stock, 50 cents might. Whatever distance you pick, write it down as a rule. Our guides on entry rules and turning entry and exit rules into orders show how to frame rules like this so they're easy to follow when you're busy.
3. Close or roll rather than hold through the bell
The OCC's position, as quoted in the comment letter, is that expiration risk is inherent in some multi-leg strategies, and that investors can close the spread before expiration or be prepared for either assignment outcome on Monday. Closing the position is the simplest answer. If you still want the exposure, rolling to a later expiration moves the decision away from the pin.
Limit orders can help you do this without chasing the market, with one catch: a limit order fills only at your price or better, so it may not fill if the stock is moving. Place it early enough that you have time to adjust it.
4. If you hold a spread, treat both legs as one decision
Do not leave the short leg alone and let the long leg expire, or the reverse. If the short leg is at risk, close the whole spread. If you decide to hold through, be ready for both outcomes: assigned or not assigned. Ask yourself, before Friday's close, what you will do Monday morning in each case, and whether you have the cash or margin to cover the stock.
5. Watch the gamma on expiration day
Near expiration, small moves in the stock cause big swings in an option's delta. That is why positions that looked safe at noon can look dangerous by 3:30 p.m. Our piece on options Greeks for 0DTE explains how gamma behaves as time runs out, and it is worth reading before you hold anything short into the final hour.
6. Plan for the weekend gap
The whole reason pin risk hurts is the closed-market gap. If something does go wrong and you end up with unwanted shares, you may be able to trade after hours depending on your broker, but liquidity can be thin. Our overview of after-hours options trading covers what you can and can't do outside regular hours. If the position has already moved against you, five moves before the next open gives you a structured way to respond.
A quick expiration-day checklist
- Is any short strike within my "danger distance" of the current price?
- Do I know my broker's cut-off for exercise instructions?
- Am I holding a spread where one leg could be assigned and the other not?
- Do I have the cash or margin to take assignment if it happens?
- If I leave the position open, what's my plan for Monday's open?
If you can't answer these in under a minute, close the trade.
Our perspective
We built Morningoptions for people who trade around other commitments: professionals, tradespeople and business owners who can't watch a screen all day. For them, pin risk is mostly a planning failure, not a market mystery. It happens when an expiration decision gets pushed to the last hour, and the last hour is exactly when you're busy.
That's why we put the work before the open. Our daily briefing gives ranked, specific contract ideas with entry and exit levels, so the exit is part of the trade from the first minute. When your plan already says where you close a short near the strike and when you roll, the expiration-day scramble mostly disappears.
Our five-step AI pipeline vets each idea against live market data, catalysts such as earnings and corporate news, and a bear case. We designed it that way because the events that cause early assignment and bad expirations, like ex-dividend dates and takeover headlines, are usually visible in advance if someone checks. Our aim is to surface those before you commit.
The Pro tier adds a lunchtime scanner and an AI chat scanner, which helps when a position you hold moves to a strike you didn't expect and you need to look at the chain fast. Pin risk punishes slow decisions, and tools that shorten the research step are built for exactly that.
Customer
Put a plan around your next expiration
If you trade options on a schedule that doesn't revolve around the market, the most useful habit is a pre-open routine: check what's expiring, check what's near a strike, and decide before the day starts. Morningoptions delivers a free daily briefing with ranked contract ideas, and the Pro plan at $89 per month (or $742 per year) adds the lunchtime scanner, Signal Lab for on-demand scans and fuller briefings.
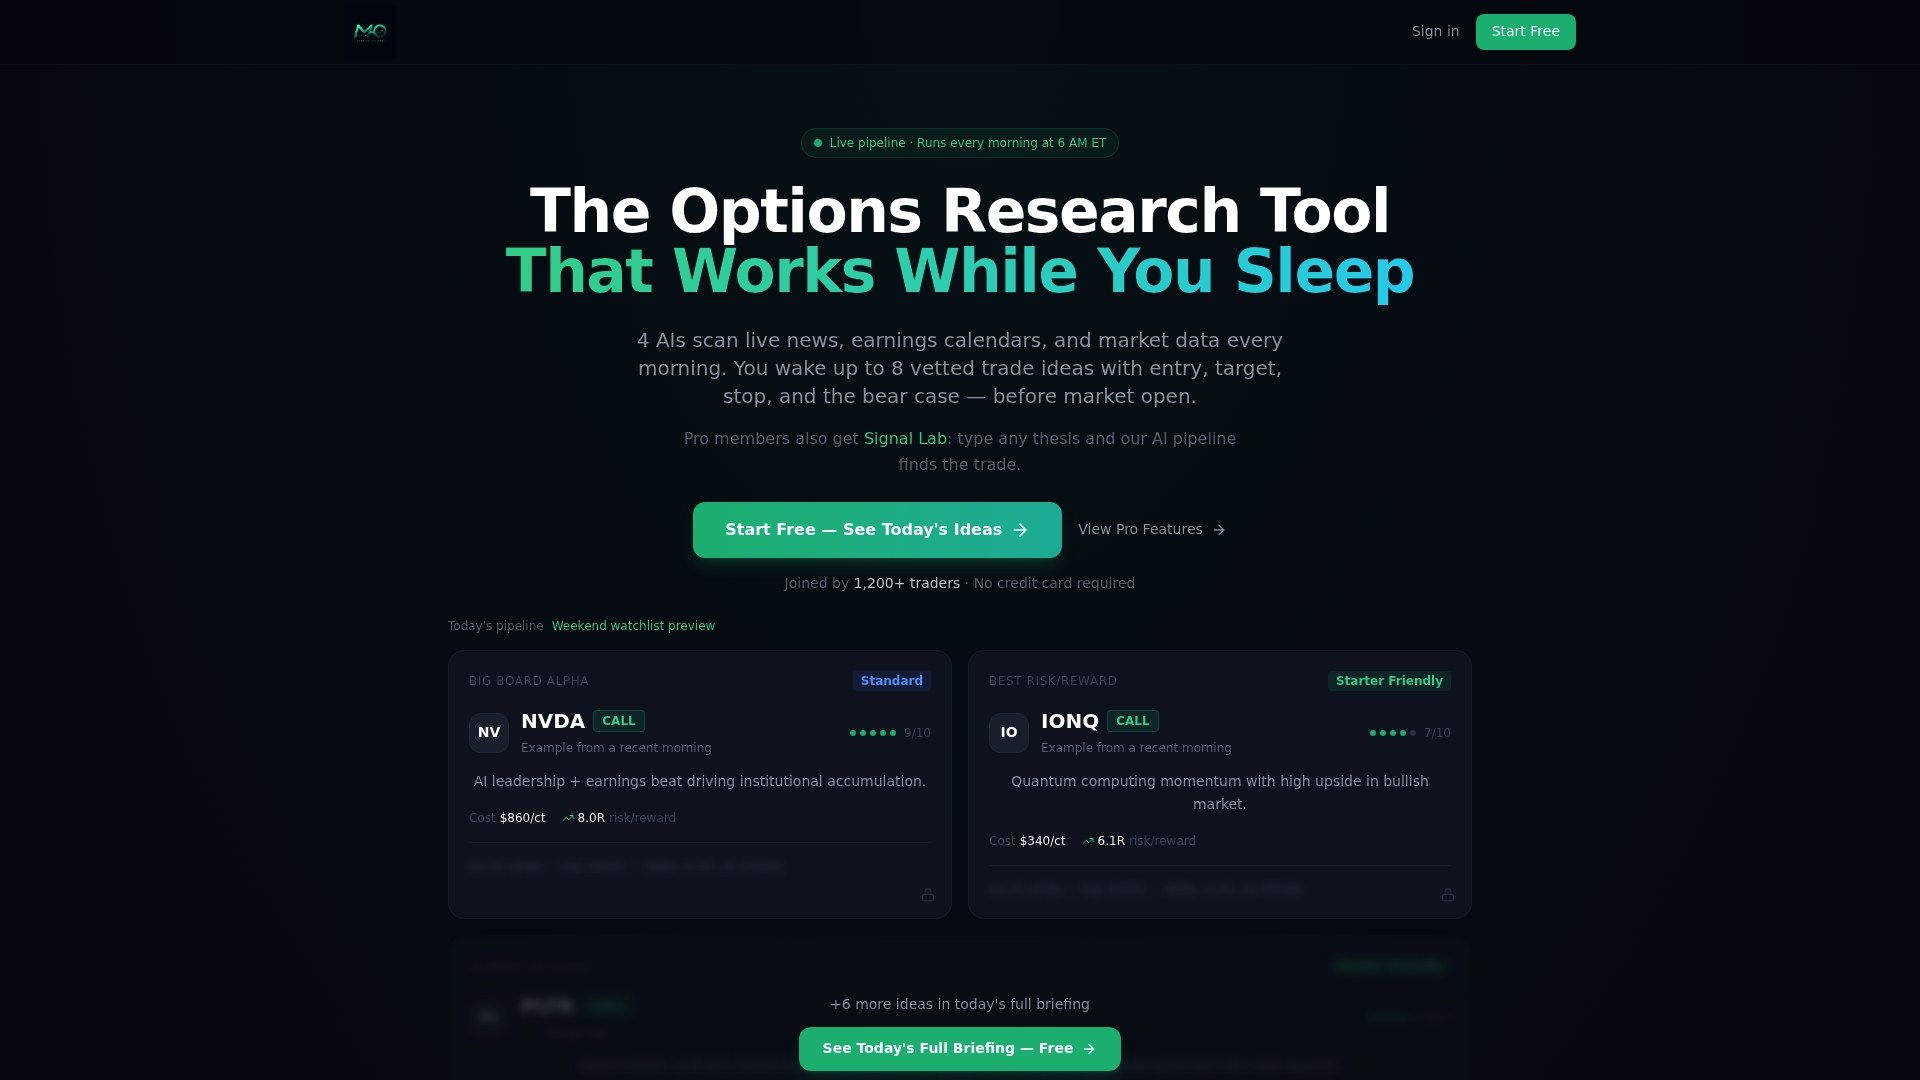
You can start with the free plan and see how the briefings fit your routine on the Morningoptions home page. If you want to build the exit side of your trades first, our pre-market entry and exit rule templates are a good starting point.
FAQ
What is pin risk in options?
Pin risk is the uncertainty a trader faces when the underlying stock closes at or very near the strike at expiration. You don't know whether your short option will be exercised, so you may end up with a long or short stock position after the market closes. If the stock gaps before trading resumes, that unplanned position can lose money.
Can I be assigned on an option that is only a few cents in the money?
Yes. U.S. listed equity options that finish at least $0.01 in the money are automatically exercised unless the holder gives contrary instructions through their broker. A holder could decide not to exercise for a tiny gain, so you can't count on either outcome. Treat a short option that close to the strike as a live assignment risk.
What is early assignment risk?
It is the chance that the writer of an American-style option is assigned before expiration. According to Interactive Brokers' educational lesson, this typically happens when the holder wants to capture a dividend or the stock is hard to borrow. If you're assigned, you must deliver or buy 100 shares at the strike.
How do I avoid pin risk with a vertical spread?
Close the spread before expiration, or roll it, instead of letting it ride through the close. Holding a multi-leg position means you may not learn which leg was assigned until the next business day, as the OCC's comment on FINRA's rules notes. If you do hold through, plan for both outcomes first.
Is early exercise risk the same as early assignment risk?
They describe the same event from opposite sides. Early exercise is the holder's decision to use the option before expiration, which usually gives up remaining time value. Early assignment is what the writer experiences as a result. Ex-dividend dates and hard-to-borrow stocks are the common triggers.
Sources
- Pin Risk in Options: Insights and Management Strategies (Investopedia)
- Understanding Pinning the Strike in Options Trading (Investopedia)
- Are You Paying Attention to Pin-Risk? (Nasdaq)
- FINRA Complex Products and Options, OCC comment letter
- Exercise and Assignment, Traders' Academy (Interactive Brokers)
- Trading Options: Understanding Assignment (FINRA)
- Unusual Trading Activity: Volume, Open Interest and Source Context