The Greeks measure how much an option's price will move when the stock moves, time passes, or volatility shifts. Delta tells you direction risk, Gamma tells you how fast that risk changes, Theta tells you the typical daily cost of holding the position, and Vega tells you your exposure to a change in implied volatility. Here's what to do with that right now:
- Pull up the chain and add columns for Delta, Gamma, Theta, and Vega for every strike you're considering, not just the one you like.
- Run the position through an options calculator and shock the price and implied volatility at the same time, since they almost never move alone.
- Multiply every Greek by your contract count before you size the trade, because a single contract's numbers mean nothing at position level.
Stick around for a full numeric walkthrough later in this piece, plus a calculator checklist you can reuse on every trade idea you evaluate.
Key Takeaways
Reading options Greeks correctly means treating Delta, Gamma, Theta, and Vega as one connected system, never in isolation, and always stress-testing them together before you size a trade.
| Point | Details |
|---|---|
| Read the full chain | Add Delta, Gamma, Theta, and Vega columns for every strike you're comparing, not just your favorite. |
| Stress-test simultaneously | Shock price and implied volatility together in a calculator, since they rarely move alone. |
| Size at the position level | Multiply per-contract Greeks by contract count before deciding how much to risk. |
| Watch liquidity, not just Greeks | Wide spreads and thin open interest make displayed Greeks unreliable in fast markets. |
| Let a scanner do the daily scan | Morningoptions ranks Greek-aware trade ideas each morning so you're not calculating every chain by hand. |
Table of Contents
- What Determines the Greeks You See on a Chain
- The Five Core Greeks and How to Read Each One
- How Delta, Gamma, and Theta Interact in a Real Trade
- Where the Greeks Can Mislead You
- A Worked Example: Reading Greeks Before You Trade
- How Pros Hedge, Rebalance, and Filter for Greek-Based Setups
- Where Most Traders Get the Greeks Wrong
- A Faster Way to Monitor Greeks Across Every Trade Idea
- Tools and Reading to Go Deeper on the Greeks
- Frequently Asked Questions
- Sources
What Determines the Greeks You See on a Chain
The Greeks aren't measured. They're calculated, produced by an option pricing model, typically some variant of Black-Scholes, that takes a handful of inputs and spits out sensitivities. Those inputs are stock price, strike price, time to expiration, implied volatility, interest rates, and dividends, and the model assumes a particular relationship between them holds true.
During market hours, two of those inputs move constantly: the stock price ticks with every trade, and implied volatility shifts with order flow, news, and the overall mood of the market. The rest, strike price, days to expiration, dividend schedule, barely move at all intraday. That asymmetry matters. A Greek you read at 9:35 AM can look meaningfully different by 2:00 PM purely because IV drifted, even if the stock hasn't moved a cent.
You'll find these figures displayed live on most broker chains, and you can recompute them yourself in an interactive options calculator when you want to test a hypothetical instead of trusting a stale quote. That distinction, live chain data versus a calculator you control, comes up again in the worked example below.
The Five Core Greeks and How to Read Each One
Each Greek answers a different question about the same contract. Learning to read them together, rather than fixating on one, is what separates traders who size positions well from traders who get blindsided by a move that "shouldn't have hurt that much."
Delta measures how much the option's price changes for a $1 move in the underlying stock. Call deltas run from 0 to +1.00, put deltas run from -1.00 to 0, and an at-the-money option typically sits near 0.50. Traders also use Delta as a rough probability gauge for finishing in the money. A 0.30 Delta call can be roughly interpreted as the market pricing a moderate chance of expiring ITM. Buyers of high-Delta options are paying up for conviction; sellers of low-Delta options are collecting premium for a bet they think won't hit.
Gamma measures how fast Delta itself changes. It peaks at the money and shrinks as strikes move deep ITM or OTM. High Gamma means your directional exposure can swing hard on a single move in the stock, which is exactly why option buyers near expiration love it and short-premium sellers fear it.
Theta is the daily cost of time. It's usually negative for long calls and long puts, meaning the position loses value every day the stock sits still, and that decay accelerates as expiration approaches. Sellers collect this decay; buyers pay it.
It runs highest for at-the-money options with more time left, which is why long-dated straddles are the classic way to play a volatility spike, and why that same position bleeds hard once IV collapses.
Rho measures sensitivity to interest rate changes. It matters least of the five for short-dated trades and matters more for longer-dated LEAPS, where a rate shift has more time to compound into the pricing model.
| Greek | Measures sensitivity to | Typical range | Peaks near | Trader takeaway |
|---|---|---|---|---|
| Delta | $1 stock move | 0 to 1 (calls), -1 to 0 (puts) | Deep ITM | Direction and rough probability of finishing ITM |
| Gamma | Delta's rate of change | Small positive number | At the money | High near expiration, drives fast P&L swings |
| Theta | One day of time passing | Negative for long options | Near-term, ATM | Daily cost for buyers, daily income for sellers |
| Vega | 1% change in implied volatility | Positive for long options | ATM, longer-dated | Exposure to IV expansion or crush |
| Rho | Interest rate shift | Small, grows with duration | Longer-dated options | Mostly relevant for LEAPS |
A few minor Greeks show up once you're managing bigger books: Vomma (Vega's sensitivity to volatility itself), Charm (Delta's decay over time), and Lambda (percentage leverage). None of them belong on a beginner's chain, but they matter once you're running multi-leg spreads where second-order effects start to compound.
How Delta, Gamma, and Theta Interact in a Real Trade
Think of Delta as speed and Gamma as acceleration. Delta tells you how fast the option's value is currently moving relative to the stock; Gamma tells you how quickly that speed itself is changing. A position with high Gamma can go from "barely directional" to "basically stock" within a single strong move, which is exactly why Gamma matters most for non-small moves in the underlying rather than the small drifts that dominate a quiet trading day.
That relationship drives a handful of rules-of-thumb worth internalizing:
- High Theta setups tend to favor sellers, but they come bundled with high Gamma risk if the stock breaks out.
- High Vega setups favor buyers who expect implied volatility to expand, typically ahead of earnings or a macro catalyst.
- If you want low Gamma exposure, move further from the money or further out in expiration. Both actions flatten the curve.
- If you want positive Theta without taking on outsized directional risk, defined-risk credit spreads let you collect decay while capping the Gamma blowup a naked short position would face.
- If you want low Vega exposure, shorter-dated, further OTM contracts carry less sensitivity to an IV crush than long-dated ATM ones.
Before placing any order, check strike and expiry against what you actually want exposure to. A trader chasing a quick earnings pop wants Gamma and Vega. A trader collecting weekly income wants Theta and as little Gamma as the strategy allows.
Where the Greeks Can Mislead You
Every Greek on your screen comes from a model, and that model rests on assumptions that don't always hold: continuous trading, log-normal returns, and constant volatility between recalculations. Markets don't actually behave that cleanly, and the gap between the model's assumptions and reality is where traders get hurt.
A few specific failure modes show up again and again:
- Earnings and IV shocks. Implied volatility can collapse the moment a catalyst passes, crushing Vega-heavy positions even when the stock barely moves.
- Overnight gaps. A stock that gaps 8% at the open blows through the small, continuous moves the model assumes, and Gamma exposure you thought was manageable suddenly isn't.
- Illiquidity and wide spreads. Thinly traded strikes show Greeks calculated off a stale or midpoint price, not a price you could actually transact at.
- Expiration-week Gamma. Gamma typically increases sharply in the last days before expiration, especially for at-the-money strikes, turning a modest move into an outsized swing in position value.
The practical fix is to stress-test more than one variable at once in a calculator, keep size conservative on anything with high Gamma or Vega, use limit orders on wide-spread names, and check open interest and bid/ask width before you trust the Greeks a chain is showing you.
A Worked Example: Reading Greeks Before You Trade
Say a stock trades at $100. A typical calculator run on that setup produces something close to: Delta 0.52, Gamma 0.04, Theta negative $0.06 per day, Vega $0.11.
- Price move check. If the stock rises $2 to $102, the option gains roughly $1.04 from Delta alone (0.52 × $2), plus a bit more from Gamma pushing Delta higher as the move happens.
- Time decay check. Sit still for three days and Theta alone costs you about $0.18 (3 × $0.06), even if the stock hasn't budged.
- Volatility move check. If implied volatility jumps from 30% to 35%, a 5-point increase, Vega adds roughly $0.55 (5 × $0.11) to the option's price.
- Position-level math. Buy 10 contracts and multiply everything by 10: Theta becomes a multiple-day drag, Vega becomes a multiple-dollar swing for a moderate IV move.
That's the exact structure Interactive Brokers uses in its own numeric Greeks walkthrough, and it's worth replicating on your own calculator before every trade, not just this one.
Pro Tip: Never shock price or IV in isolation. Run them together, since a rallying stock ahead of earnings usually means both are moving at once, and the combined effect on your position rarely equals the sum of the two separate estimates.
How Pros Hedge, Rebalance, and Filter for Greek-Based Setups
Professional desks use Delta hedging to strip directional risk out of a position, typically by trading the underlying shares against it. Shares give a pure Delta offset, one share always equals 1.0 Delta, with no residual Gamma, Theta, or Vega attached the way an offsetting option position would carry. That's why desks reach for shares when the goal is pure directional neutrality, and reach for other options when the goal is Delta-Gamma or Delta-Vega neutrality instead.
Rebalancing cadence depends on cost tolerance. Some desks rebalance daily regardless of size; others wait for Delta to drift outside a fixed band, say plus or minus 0.10 at the position level; others rebalance only around scheduled events like earnings or Fed announcements. Frequent rebalancing keeps a book tighter to neutral but racks up transaction costs that eat into edge, which is exactly why the cadence decision matters as much as the hedge itself.
If you're building your own scanner filter to surface tradable setups, a workable starting checklist looks like this:
- Set a target portfolio Delta band (many retail traders aim to stay within plus or minus 20% of account value in net Delta exposure).
- Cap Gamma per position so no single name can flip your book's directional exposure overnight.
- Define your Vega appetite based on whether you're hunting IV expansion or avoiding it.
- Filter for liquidity, tight bid/ask spreads and reasonable open interest keep your live Greeks trustworthy instead of theoretical.
- Backtest execution costs against your rebalancing rule before assuming a cadence is actually profitable after fees and slippage.
Where Most Traders Get the Greeks Wrong
The most common mistake I see is fixating on Delta and ignoring everything else. A trader picks a strike because "it's got 70 Delta, good odds," then gets surprised when a volatility crush after earnings costs more than the directional move made. Delta alone tells you almost nothing about your Vega or Theta exposure sitting right next to it.
The second mistake is treating implied volatility as background noise instead of a live risk factor. IV isn't a static input; it's arguably the most important one during earnings season, and skipping it means you're pricing half the risk in your own position.
The third mistake is testing one variable at a time in a calculator instead of stacking price and IV shocks together, which is precisely how real market moves tend to unfold.
A workable path forward: read your chain's Greek columns daily, even on trades you're not taking, just to build pattern recognition. Run every serious candidate through a calculator with simultaneous price and IV shocks before entering. And once you're holding more than one position, build a simple spreadsheet that sums Delta, Gamma, Theta, and Vega across your whole book, not just per trade. While you're building that muscle, lean on defined-risk structures like spreads rather than naked options. They cap the downside while you're still learning to read the second-order effects that catch newer traders off guard.
A Faster Way to Monitor Greeks Across Every Trade Idea
Reading Greeks manually across dozens of chains every morning is realistic for a full-time trader. It's a lot less realistic if you've got a job, a business, or anything else competing for your attention before the market opens.
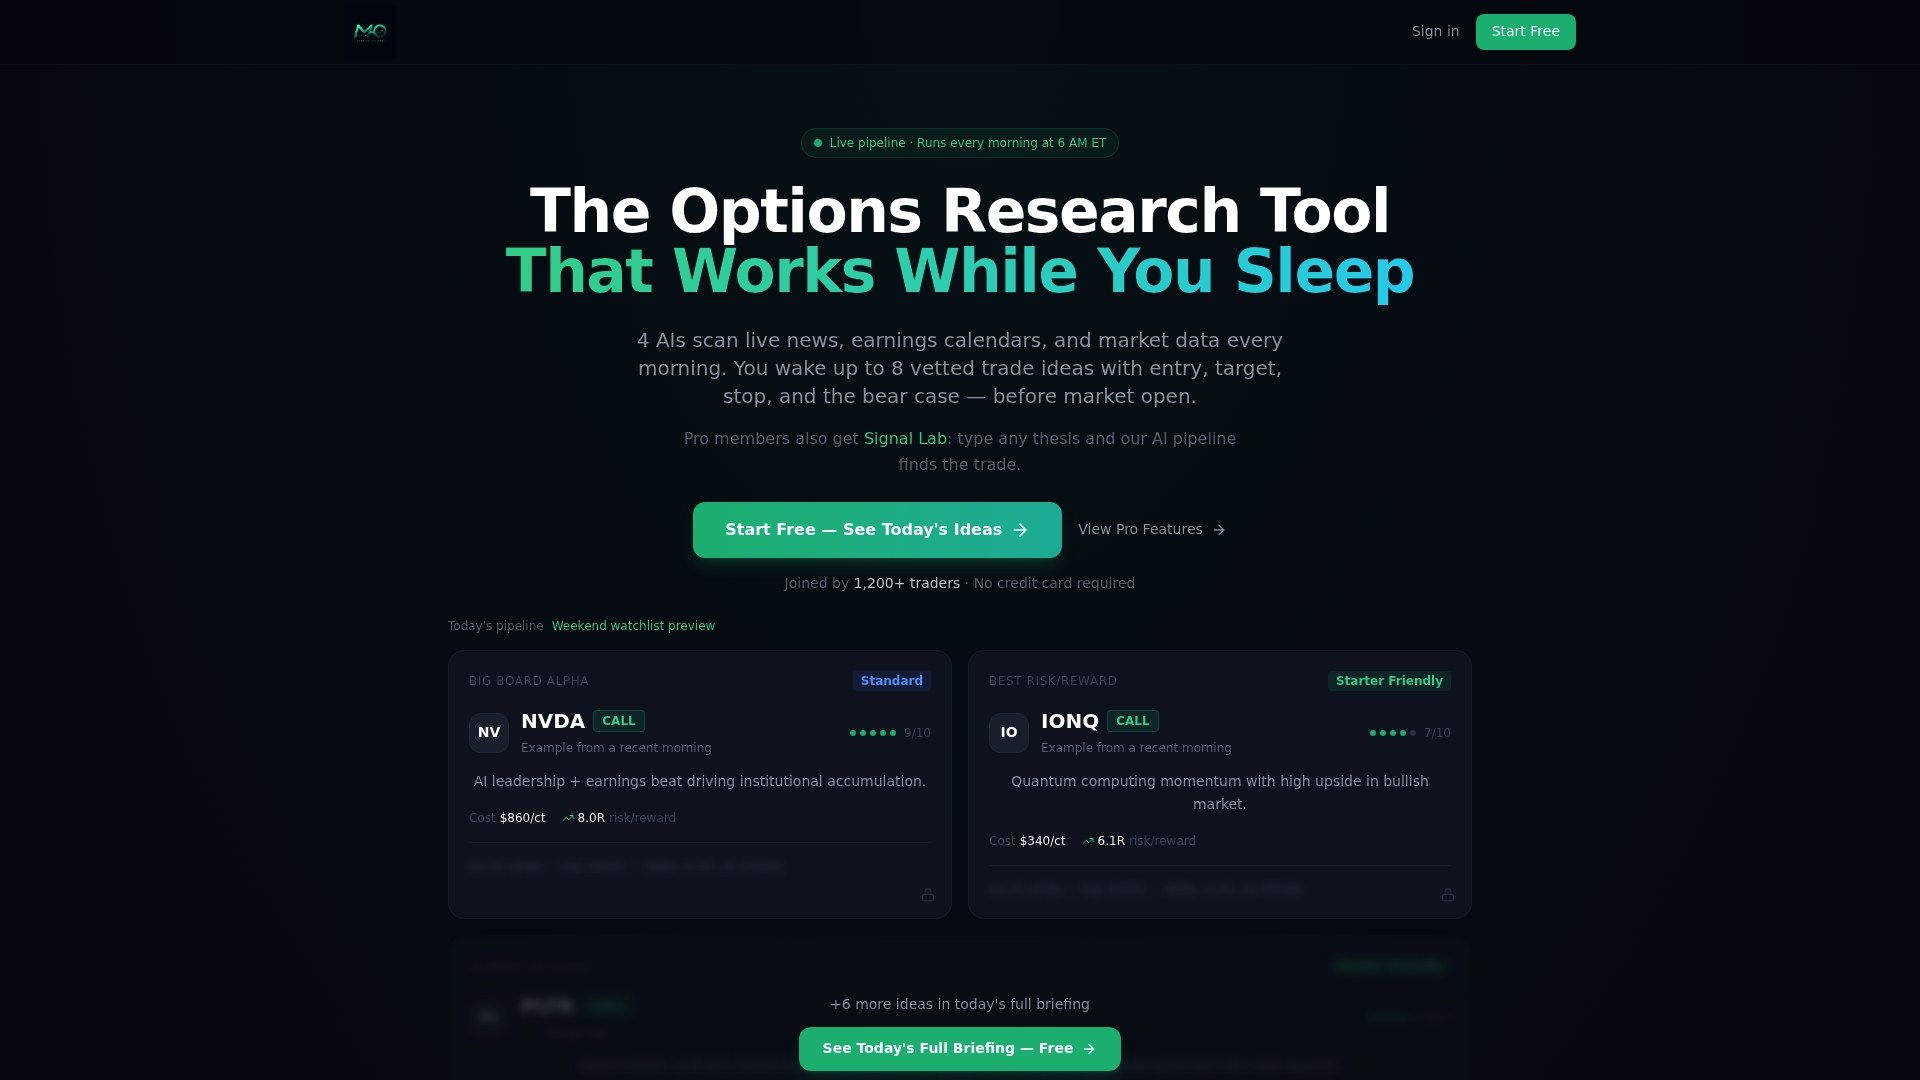
That's where a scanner built specifically for options traders earns its keep. Morningoptions runs a daily AI pipeline that filters the chain, scores setups, and flags entry and exit levels before you'd even finish your coffee, which means the Delta, Gamma, and Vega checks covered in this guide are already baked into the ranking instead of something you calculate strike by strike. The free daily briefing gets you ranked ideas every market morning, and the Pro tier at $89 a month adds a midday scanner plus an on-demand chat tool for pulling Greek-aware reads on any ticker you're watching. If you want to see how the scoring actually treats these sensitivities, the Morningoptions options scoring breakdown walks through it, or you can check today's briefing directly and see what the scanner is surfacing this morning.
Tools and Reading to Go Deeper on the Greeks
- OIC Options Calculators: free interactive calculators for testing theoretical prices and Greeks when you want to model a hypothetical trade before entering it.
- Interactive Brokers' Greeks lesson: a broker education walkthrough with a full numeric example covering all five Greeks in one worked scenario.
- Intrinsic vs. extrinsic value breakdown: useful for understanding what part of an option's price the Greeks are actually measuring changes to.
- Options strategies for volatile markets: applies Vega and Theta concepts directly to strategy selection when implied volatility is elevated.
- Defined-risk trade ideas: structures worth practicing on while you're still building comfort reading Gamma and Vega exposure.
Frequently Asked Questions
What's the fastest way to read options Greeks on a chain? Add Delta, Gamma, Theta, and Vega as columns on your broker's chain, then compare them across strikes side by side rather than checking one contract at a time. Most platforms let you customize which columns display by default.
Which Greek matters most for a beginner? Delta and Theta together, since they answer the two questions beginners care about most: how directional is this trade, and what does it cost me to hold it each day. Vega becomes critical the moment you're trading around earnings.
Can Greeks be wrong? They're not "wrong" so much as estimates built on a model's assumptions. When implied volatility spikes, a stock gaps, or liquidity dries up, actual price behavior can diverge meaningfully from what the Greeks predicted going in.
How often should I rebalance a delta-hedged position? It depends on your cost tolerance. Daily rebalancing keeps a book tighter to neutral but adds transaction costs; a fixed Delta band or event-driven approach cuts costs but tolerates more drift between adjustments.
Do I need to understand every Greek before I start trading options? No. Get comfortable with Delta, Gamma, and Theta first, since those drive most single-leg outcomes. Add Vega once you're trading around earnings or other volatility catalysts, and treat Rho and the minor Greeks as advanced-book concerns.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Foundations of Financial Engineering: The Black-Scholes model (Columbia University notes)
- Understanding Options Greeks (Options Industry Council)
- Getting to Know the Greeks (Investopedia)
- Introduction to Options – The Greeks (Interactive Brokers)
- Delta Hedging: Dynamic Risk Management (The Option Stack)